Non classé
Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First

Published
8 heures agoon
By
Warehouse automation announcements tend to celebrate the beginning. A new distribution center opens. Robots arrive. An automated storage and retrieval system goes live. Executives talk about throughput, labor savings, and future growth. But perhaps the more revealing warehouse automation story begins several years later, when a company decides whether to do it again. That is what makes the latest development involving Cutter & Buck, Kardex, and AutoStore particularly interesting.
Cutter & Buck, the apparel company, recently opened a new distribution center in Grand Prairie, Texas, featuring its second AutoStore goods-to-person system implemented by Kardex. The system includes 50,502 storage bins, 32 R5 Pro robots, and 13 ports, with Kardex FulfillX warehouse execution software coordinating the operation. It is designed for 1,256 bin presentations per hour, with simulation results averaging 1,284.
Those numbers are interesting. But the more important number may be two. This is not Cutter & Buck’s first attempt at warehouse automation. And that changes the story.
The First Warehouse Was the Experiment
Cutter & Buck began its earlier automation journey at its Renton, Washington, distribution center, where a Kardex-deployed AutoStore system went live in July 2023 with more than 34,000 bins and 54 robots. As the operation grew, the company later added another 9,962 storage bins along with additional ports and infrastructure. That evolution matters because the Texas facility was not designed simply by copying Renton.
According to Kardex, the companies used several years of operating experience, performance data, and lessons from the first deployment to shape the new distribution center around Cutter & Buck’s changing fulfillment requirements. This is where the story becomes much more useful for warehouse executives. There is an enormous difference between asking, “Should we automate?” and asking, “Knowing what we know after three years of automation, how should we automate the next building?” The second question may tell us far more about automation maturity.
What Happened After the Robots Arrived?
The publicly reported results from the original Renton deployment provide important context. In its case study, Kardex reports that Cutter & Buck reduced peak-season labor requirements by 60%, with 12 associates handling workloads that previously required 30. The company also reports that online orders can move from order to shipment in as little as 10 minutes.
Those are precisely the kinds of metrics automation buyers should be looking for. A warehouse can look highly automated without necessarily being highly productive. The business case ultimately depends on what happens to labor requirements, order cycle time, accuracy, capacity, service levels, and cost per order. That is especially important for Cutter & Buck because its fulfillment profile involves more than simply retrieving apparel from storage.
Nearly half of picking activity at the Renton operation supports embroidery workflows, according to the Kardex case study. That means products have to flow not just from storage to shipping, but through value-added customization processes as well. The Texas facility reflects that complexity. Its conveyor system connects AutoStore output with embroidery, order routing, Print & Apply, and shipping processes. In other words, the interesting technology story is no longer simply automated storage. It is automated flow.
The Second Warehouse Is the Real Vote of Confidence
Warehouse automation vendors understandably highlight initial customer wins. From an analyst perspective, however, repeat investment can be more revealing. A first implementation is based largely on expectations: projected throughput, anticipated labor savings, simulations, reference customers, and a calculated ROI. A second investment can be based on something much more valuable: the customer’s own operating data.
Cutter & Buck had several years to see how its first AutoStore deployment performed, expand that system as SKU requirements increased, identify where workflows could be improved, and then decide how to approach its next distribution center. It chose automation again. That does not mean every warehouse operator should reach the same conclusion. But it does suggest an important way customers should evaluate suppliers. Do not look only at how many new customers a technology provider wins. Look at how many existing customers expand, add robots or ports, increase storage capacity, or deploy the technology in another building. Those decisions occur after the sales presentation is over.
Modular Automation Changes the Economics
There is another important aspect of the Cutter & Buck example: scalability. At Grand Prairie, the number of robots and ports can be expanded independently as demand changes. That matters because one of the hardest parts of warehouse automation investment is forecasting the future.
Volumes change. SKU counts increase. Customer expectations shift. Peak seasons become more pronounced. A system designed perfectly for today’s demand may be poorly sized five years from now. Modular systems potentially give operators another way to think about ROI. Instead of asking whether they can perfectly forecast requirements over the entire investment horizon, they can ask whether the underlying automation architecture gives them enough room to respond when that forecast inevitably changes.
Cutter & Buck’s Renton facility illustrates that point particularly well. The original system was not frozen in its 2023 configuration. It subsequently expanded by nearly 10,000 additional bins as the business required more capacity. That ability to expand deserves more attention in automation business cases.
Stop Asking Only About Day-One Throughput
The warehouse automation market often focuses heavily on commissioning and initial throughput. Those metrics matter. But mature automation decisions should examine a longer timeline. What happened after year one?
Did the operation require more people than anticipated? What happened during peak? Could the system absorb additional SKUs? How expensive was maintenance? Could throughput be expanded without redesigning the facility? And most importantly, when the company needed another distribution center, did management choose the technology again? Research suggests these questions remain relevant. The 2026 Intralogistics Robotics Study surveyed 166 warehouse, distribution, and manufacturing professionals involved in robotic automation decisions. While 74% of organizations already deploying robots said they achieved their business goals, the study found a more complicated picture around cost and time to value.
That is an important distinction. Successful automation is not simply automation that works. It is automation capable of continuing to make economic sense as the operation changes.
Takeaway
The most interesting part of the Cutter & Buck, Kardex, and AutoStore story is not 32 robots or 50,502 bins. It is repeatability. Cutter & Buck implemented warehouse automation, operated it for several years, expanded it, learned from it, and then used those lessons to build another automated distribution operation. For companies evaluating AS/RS and goods-to-person technologies, that provides a useful lesson. Don’t just ask a supplier to show you its newest installation. Ask to see the customer that came back for the second one. That may be one of the clearest indicators that warehouse automation has moved from an impressive technology project to a sustainable operating strategy.
The post Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First appeared first on Logistics Viewpoints.
You may like
Non classé
Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First
Published
8 heures agoon
5 novembre 2026By
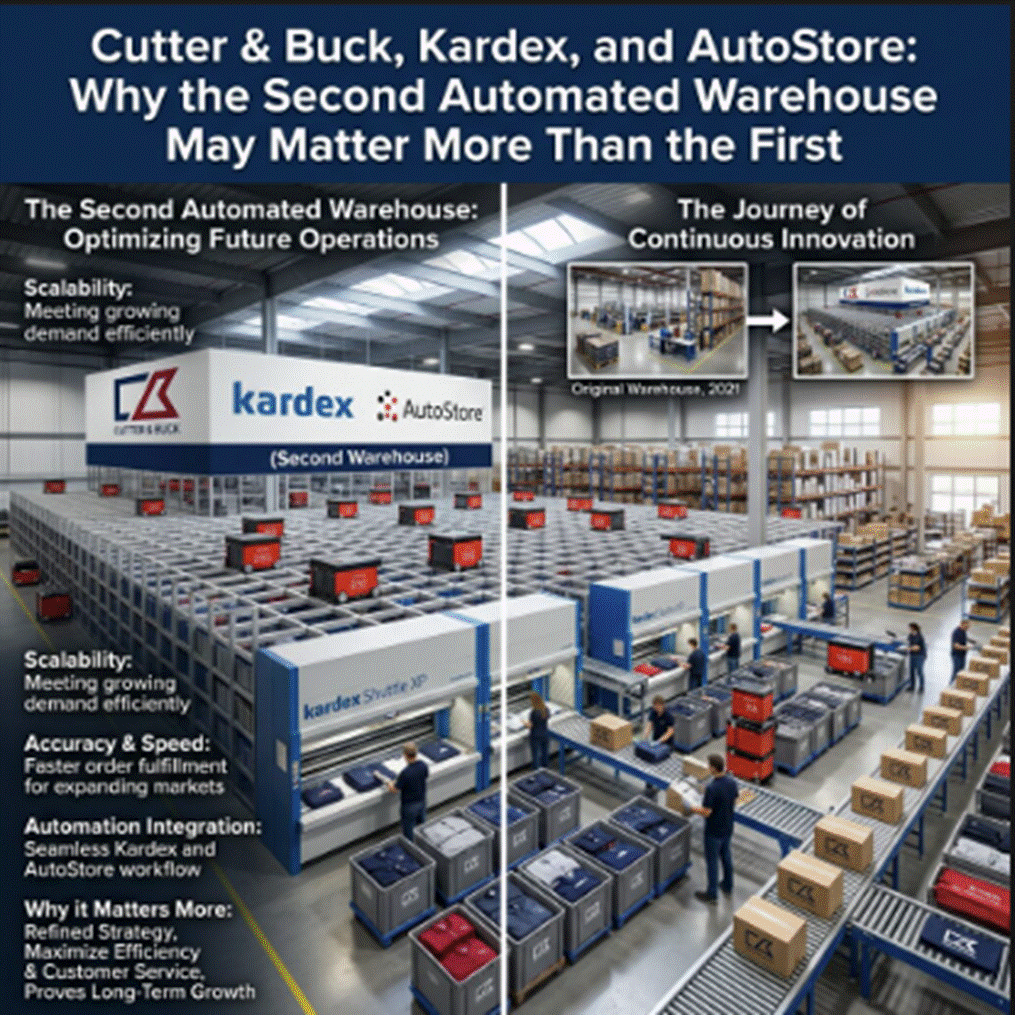
Warehouse automation announcements tend to celebrate the beginning. A new distribution center opens. Robots arrive. An automated storage and retrieval system goes live. Executives talk about throughput, labor savings, and future growth. But perhaps the more revealing warehouse automation story begins several years later, when a company decides whether to do it again. That is what makes the latest development involving Cutter & Buck, Kardex, and AutoStore particularly interesting.
Cutter & Buck, the apparel company, recently opened a new distribution center in Grand Prairie, Texas, featuring its second AutoStore goods-to-person system implemented by Kardex. The system includes 50,502 storage bins, 32 R5 Pro robots, and 13 ports, with Kardex FulfillX warehouse execution software coordinating the operation. It is designed for 1,256 bin presentations per hour, with simulation results averaging 1,284.
Those numbers are interesting. But the more important number may be two. This is not Cutter & Buck’s first attempt at warehouse automation. And that changes the story.
The First Warehouse Was the Experiment
Cutter & Buck began its earlier automation journey at its Renton, Washington, distribution center, where a Kardex-deployed AutoStore system went live in July 2023 with more than 34,000 bins and 54 robots. As the operation grew, the company later added another 9,962 storage bins along with additional ports and infrastructure. That evolution matters because the Texas facility was not designed simply by copying Renton.
According to Kardex, the companies used several years of operating experience, performance data, and lessons from the first deployment to shape the new distribution center around Cutter & Buck’s changing fulfillment requirements. This is where the story becomes much more useful for warehouse executives. There is an enormous difference between asking, “Should we automate?” and asking, “Knowing what we know after three years of automation, how should we automate the next building?” The second question may tell us far more about automation maturity.
What Happened After the Robots Arrived?
The publicly reported results from the original Renton deployment provide important context. In its case study, Kardex reports that Cutter & Buck reduced peak-season labor requirements by 60%, with 12 associates handling workloads that previously required 30. The company also reports that online orders can move from order to shipment in as little as 10 minutes.
Those are precisely the kinds of metrics automation buyers should be looking for. A warehouse can look highly automated without necessarily being highly productive. The business case ultimately depends on what happens to labor requirements, order cycle time, accuracy, capacity, service levels, and cost per order. That is especially important for Cutter & Buck because its fulfillment profile involves more than simply retrieving apparel from storage.
Nearly half of picking activity at the Renton operation supports embroidery workflows, according to the Kardex case study. That means products have to flow not just from storage to shipping, but through value-added customization processes as well. The Texas facility reflects that complexity. Its conveyor system connects AutoStore output with embroidery, order routing, Print & Apply, and shipping processes. In other words, the interesting technology story is no longer simply automated storage. It is automated flow.
The Second Warehouse Is the Real Vote of Confidence
Warehouse automation vendors understandably highlight initial customer wins. From an analyst perspective, however, repeat investment can be more revealing. A first implementation is based largely on expectations: projected throughput, anticipated labor savings, simulations, reference customers, and a calculated ROI. A second investment can be based on something much more valuable: the customer’s own operating data.
Cutter & Buck had several years to see how its first AutoStore deployment performed, expand that system as SKU requirements increased, identify where workflows could be improved, and then decide how to approach its next distribution center. It chose automation again. That does not mean every warehouse operator should reach the same conclusion. But it does suggest an important way customers should evaluate suppliers. Do not look only at how many new customers a technology provider wins. Look at how many existing customers expand, add robots or ports, increase storage capacity, or deploy the technology in another building. Those decisions occur after the sales presentation is over.
Modular Automation Changes the Economics
There is another important aspect of the Cutter & Buck example: scalability. At Grand Prairie, the number of robots and ports can be expanded independently as demand changes. That matters because one of the hardest parts of warehouse automation investment is forecasting the future.
Volumes change. SKU counts increase. Customer expectations shift. Peak seasons become more pronounced. A system designed perfectly for today’s demand may be poorly sized five years from now. Modular systems potentially give operators another way to think about ROI. Instead of asking whether they can perfectly forecast requirements over the entire investment horizon, they can ask whether the underlying automation architecture gives them enough room to respond when that forecast inevitably changes.
Cutter & Buck’s Renton facility illustrates that point particularly well. The original system was not frozen in its 2023 configuration. It subsequently expanded by nearly 10,000 additional bins as the business required more capacity. That ability to expand deserves more attention in automation business cases.
Stop Asking Only About Day-One Throughput
The warehouse automation market often focuses heavily on commissioning and initial throughput. Those metrics matter. But mature automation decisions should examine a longer timeline. What happened after year one?
Did the operation require more people than anticipated? What happened during peak? Could the system absorb additional SKUs? How expensive was maintenance? Could throughput be expanded without redesigning the facility? And most importantly, when the company needed another distribution center, did management choose the technology again? Research suggests these questions remain relevant. The 2026 Intralogistics Robotics Study surveyed 166 warehouse, distribution, and manufacturing professionals involved in robotic automation decisions. While 74% of organizations already deploying robots said they achieved their business goals, the study found a more complicated picture around cost and time to value.
That is an important distinction. Successful automation is not simply automation that works. It is automation capable of continuing to make economic sense as the operation changes.
Takeaway
The most interesting part of the Cutter & Buck, Kardex, and AutoStore story is not 32 robots or 50,502 bins. It is repeatability. Cutter & Buck implemented warehouse automation, operated it for several years, expanded it, learned from it, and then used those lessons to build another automated distribution operation. For companies evaluating AS/RS and goods-to-person technologies, that provides a useful lesson. Don’t just ask a supplier to show you its newest installation. Ask to see the customer that came back for the second one. That may be one of the clearest indicators that warehouse automation has moved from an impressive technology project to a sustainable operating strategy.
The post Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First appeared first on Logistics Viewpoints.
Non classé
Kinaxis Reports 22% SaaS Growth in Q3 2026, Raises Full-Year Outlook
Published
10 heures agoon
5 novembre 2026By
Kinaxis reported strong third-quarter 2026 financial results, with continued growth in cloud-based supply chain software, expanding customer adoption, and an increased full-year financial outlook. The results reflect sustained demand for supply chain planning and orchestration technology as manufacturers and distributors seek greater visibility, agility, and coordination across increasingly complex operations.
For the quarter ended September 30, Kinaxis generated $160.3 million in total revenue, an increase of 19% year-over-year. SaaS revenue rose 22% to $112.3 million, while annual recurring revenue (ARR) increased 19% to $483.9 million. Remaining performance obligations exceeded $1 billion, rising 21% from the prior year.
The company also reported $20.1 million in profit and adjusted EBITDA of $42 million, representing a 26% adjusted EBITDA margin.
Customer Growth Across Industries
Kinaxis continued to expand adoption of its Maestro supply chain orchestration platform across multiple industries and geographies.
New customer wins included Dr. Squatch, Sterlite Technologies, and WAI Global, along with organizations in luxury goods, biotechnology, and consumer health. The company also reported renewals and expansions involving Clariant and Sanofi.
More than 40 customer deployments went live during the quarter, including Asahi Beverages, with additional implementations across aviation, energy, healthcare, and manufacturing.
AI and Supply Chain Orchestration
Beyond its financial performance, Kinaxis is expanding its investment in AI-driven supply chain decision-making.
At Kinexions EMEA in October, the company introduced additional agentic AI capabilities, advanced inventory optimization, and enhancements to its Kinaxis Data Fabric. These developments are designed to help organizations move beyond traditional planning toward more connected and responsive operational execution.
The emphasis on AI-enabled workflows and improved inventory optimization reflects a broader industry transition toward systems that can identify changing conditions, evaluate alternatives, and support faster operational decisions.
Raised 2026 Outlook
Following its third consecutive quarter of outperformance, Kinaxis raised its full-year revenue guidance to $640 million–$650 million, increased its expected SaaS revenue growth to 20%–21%, and lifted its adjusted EBITDA margin outlook to 26.5%–27.5%.
The results highlight continued enterprise investment in supply chain planning technology, particularly platforms combining advanced optimization, real-time decision support, and emerging AI capabilities. For technology providers, the challenge increasingly extends beyond offering sophisticated planning tools to demonstrating how those capabilities translate into measurable operational improvements.
Read the full Kinaxis Q3 2026 financial results.
The post Kinaxis Reports 22% SaaS Growth in Q3 2026, Raises Full-Year Outlook appeared first on Logistics Viewpoints.
Non classé
Blue Yonder Launches AI-Native Order Management for Retailers and Distributors
Published
10 heures agoon
5 novembre 2026By
Blue Yonder announced today the launch of its AI-native Order Management Solution, extending its Cognitive Solutions portfolio with capabilities designed to connect inventory, fulfillment, transportation, customer service, and returns around individual customer orders.
The November 5 announcement reflects a broader shift in supply chain technology: moving beyond order visibility toward coordinated decision-making and execution across traditionally separate systems.
For retailers and distributors, disconnected systems can result in inaccurate delivery promises, canceled orders, higher fulfillment costs, and slower responses to disruptions. Blue Yonder’s new solution aims to address these challenges by combining real-time inventory intelligence, AI agents, and automated order orchestration.
Connecting AI to Order Execution
The solution introduces Fulfillment and Customer Service Agents that identify at-risk orders, explain operational trade-offs, and recommend corrective actions. These capabilities operate within configurable business rules and permissions, allowing teams to respond to changing supply, demand, and capacity conditions.
Key capabilities include:
Inventory-aware order promising: Using inventory visibility across stores, distribution centers, suppliers, and goods in transit to improve delivery commitments.
Intelligent order rebalancing: Reallocating inventory and adjusting fulfillment priorities when disruptions occur.
AI-assisted exception management: Helping customer service and operations teams identify and resolve order issues.
Smarter returns disposition: Applying business rules and profitability considerations to determine whether returned products should be resold, repaired, or redirected.
The platform also addresses the complexity of B2B wholesale and distribution, where contractual commitments, future inventory availability, and customer-specific allocation priorities require more sophisticated order management than conventional consumer transactions.
Why It Matters
The significance of this announcement extends beyond adding AI functionality to an order management system. Blue Yonder is positioning order management as a coordination layer connecting supply chain planning decisions with physical execution.
For retailers and distributors, the potential value lies in reducing the time between recognizing a fulfillment problem and taking corrective action. Delivering that value will depend on reliable inventory data, integration across systems, and effective operational controls.
Blue Yonder says the cloud-native, modular solution allows organizations to adopt capabilities incrementally rather than replace their existing technology environments.
More information is available in Blue Yonder’s announcement.
The post Blue Yonder Launches AI-Native Order Management for Retailers and Distributors appeared first on Logistics Viewpoints.

Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First
Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First
Kinaxis Reports 22% SaaS Growth in Q3 2026, Raises Full-Year Outlook
Freightos Global Freight Outlook – September 2026
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update

Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
Trending
- Non classé2 mois ago
Freightos Global Freight Outlook – September 2026
- Non classé4 mois ago
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update
-
 Non classé2 ans ago
Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
-
 Non classé7 mois ago
Why Sulfuric Acid Is Emerging as a Supply Chain Constraint in Copper
- Non classé5 mois ago
Container rates starting to spike on peak season rush – June 2, 2026 Update
- Non classé1 an ago
13 Books Logistics And Supply Chain Experts Need To Read
- Non classé1 an ago
Ex-Asia ocean rates climb on GRIs, despite slowing demand – October 22, 2025 Update
- Non classé4 mois ago
LCL Shipping Cost Calculator: Calculate Air and Sea Shipping Freight Rates