Non classé
Executive Authenticity at Scale: Using Podcasts to Build Trust in Supply Chain and Logistics

Published
5 mois agoon
By
Some market stories are best told through conversation. Articles and reports are important, but they do not always capture the nuance behind executive perspective, company strategy, or market change.
That is why podcasts have become a valuable format for supply chain and logistics thought leadership. They give leaders room to explain how they see the market, why certain problems matter, and how their companies are responding to change.
For solution providers, a sponsored podcast can be more than a visibility tactic. It can be a way to communicate perspective in a format that feels accessible, substantive, and human.
Why Podcasts Work for Executive Perspective
Supply chain technology markets are often complex. A company may be addressing a problem that spans systems, processes, people, data, and operating models. Explaining that story in a short advertisement or product page can be difficult.
A podcast creates room for context. It allows an executive to describe the market problem, discuss what customers are experiencing, explain how the company thinks about the category, and connect the conversation to larger industry trends.
This is especially useful when the story involves transformation. Topics such as transportation management evolution, warehouse automation, supply chain planning, visibility, decision intelligence, global trade complexity, and AI-enabled operations often benefit from a conversational format.
Moving Beyond Scripted Messaging
Buyers can recognize scripted marketing quickly. A podcast works best when it does not sound like a commercial. The conversation should be structured, but it should also allow the guest to speak naturally and offer real perspective.
This can help create credibility. When executives explain how they think about market change, they are not simply promoting a product. They are demonstrating judgment, experience, and understanding.
That kind of credibility can matter in supply chain markets, where buyers are often evaluating providers based on trust, operational understanding, and long-term fit.
Podcasts as Market Education
A strong podcast can educate the market in a way that is different from a webinar or report. It can introduce a topic, explore a trend, or unpack a specific business issue in a format that listeners can consume while traveling, exercising, or working through a busy day.
This accessibility is valuable. Senior executives may not always have time to read a long report or attend a live event, but they may listen to a focused conversation that helps them understand where a market is heading.
For sponsors, this creates an opportunity to associate the company with a useful discussion rather than a narrow sales message.
Good Podcast Topics Start with a Market Issue
As with webinars, the best podcast topics begin with the audience’s problem. A podcast should not simply ask, “What does the company sell?” It should ask, “What is changing in the market, and what should decision-makers understand?”
A transportation technology provider might discuss why transportation management is becoming more connected to broader enterprise decision-making. A warehouse automation provider might discuss how fulfillment pressure is changing labor and systems strategy. A planning provider might discuss how volatility is reshaping the planning function. A visibility provider might discuss how the market is moving from tracking to decision support.
In each case, the sponsor’s perspective is valuable because it helps explain an issue that matters to the audience.
Extending the Life of the Conversation
A podcast can also become a durable content asset. It can be shared through newsletters, sales follow-up, social channels, account-based marketing, and related thought leadership campaigns.
It can also support other content formats. A strong podcast conversation may generate article ideas, webinar themes, executive quotes, short video clips, or sales enablement material.
This makes the podcast more than a single episode. It becomes part of a broader market narrative.
When a Sponsored Podcast Is the Right Fit
A sponsored podcast is especially useful when a company has an executive with a clear point of view, a nuanced market story, or a strategic theme that benefits from conversation.
It can be a good fit for companies that want to explain market change, introduce a category perspective, support a campaign, build executive visibility, or create a more personal connection with the audience.
In a crowded market, buyers often remember the companies that help them think more clearly. A podcast gives providers a format for doing exactly that.
CTA: Download the Sponsored Podcast Program overview to learn how executive conversations can support thought leadership, market education, and brand credibility.
If you have questions about whether a sponsored podcast fits your company’s executive visibility or market education goals, reach out to me directly at jfrazer@arcweb.com. I’d be glad to discuss where your priorities align with the Logistics Viewpoints podcast and editorial calendar.
The post Executive Authenticity at Scale: Using Podcasts to Build Trust in Supply Chain and Logistics appeared first on Logistics Viewpoints.
You may like
Non classé
Beyond the AMR: Rockwell’s Production Logistics Strategy Connects Material Flow to Plant Autonomy
Published
4 heures agoon
20 novembre 2026By
An analyst perspective on why orchestration, digital twins, and plant-floor integration matter more than the robot alone
Production logistics becomes a control problem
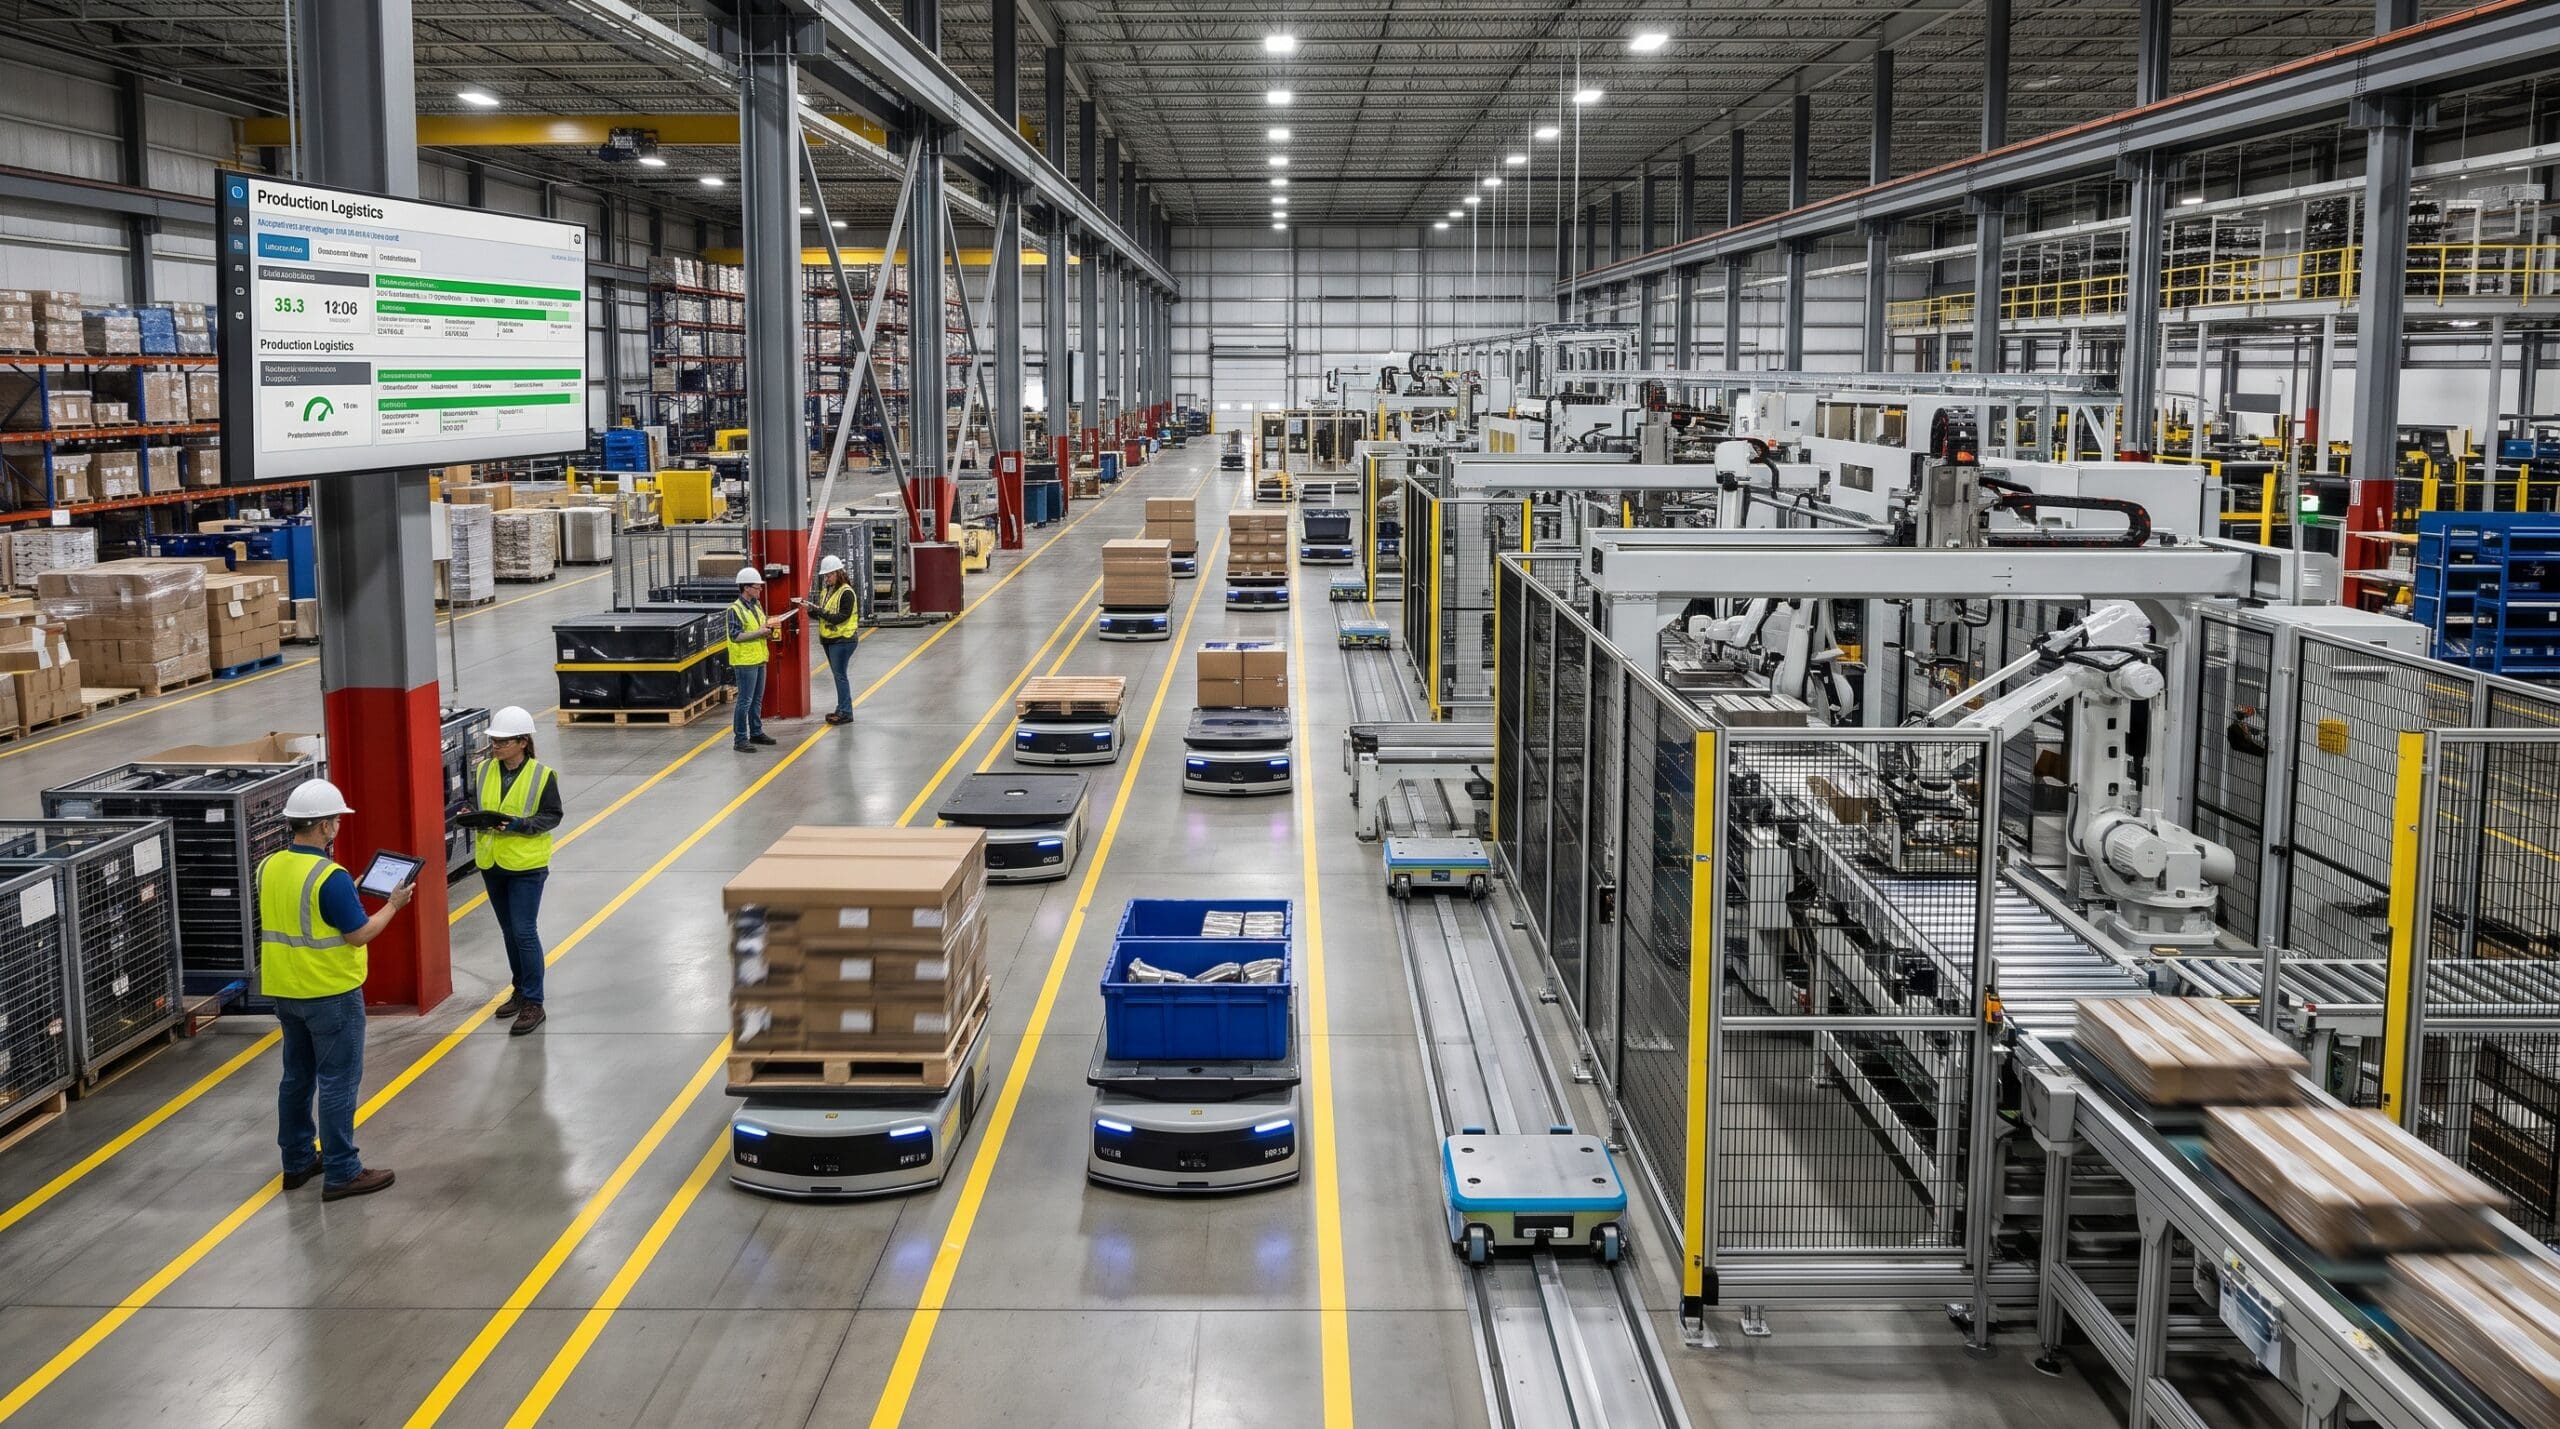
Rockwell Automation’s press conference presented a clear thesis: the next major productivity opportunity lies in the space between automated processes. Many factories have sophisticated machines and well-instrumented production lines, yet material still arrives through manual, disconnected workflows. The result is a familiar contradiction: a highly automated line can still depend on a forklift driver or an operator pushing a cart at its boundary.
“At the end of the line, there was a person driving a forklift and a person pushing a cart.”
That gap is where Rockwell is positioning production logistics. Rather than treating intralogistics as a stand-alone robotics project, the company describes an end-to-end workflow spanning production software, orchestration, controls, autonomous mobile robots, independent cart technology, and human work. This is a stronger industrial proposition than simply adding AMRs to a fleet. It treats the movement of work-in-process, components, packaging, and finished goods as part of the production system itself.
For manufacturers, the implication is significant. Material movement can become event-driven by production demand, quality status, inventory availability, and equipment conditions. The operational objective shifts from “dispatch a robot” to “maintain the production plan.”
From connected operations to autonomous response
Rockwell placed production logistics within a broader progression from connected operations to predictive and increasingly autonomous plants. Its “sense, think, act” framing is familiar in robotics, but the company extends the concept beyond the mobile robot to machines, lines, and plant-level workflows. Sensors establish context, software evaluates conditions, and physical assets execute the response, with a human retained in the loop where risk or uncertainty requires oversight.
“The right product to the right spot at the right time.”
This framing addresses one of the hardest problems in plant automation: local optimization does not automatically create system optimization. A packaging machine can be highly efficient while waiting for film. An assembly cell can meet its cycle time but starve because a component was not replenished in sequence. A warehouse can optimize picks while production priorities have already changed. The value of autonomy therefore depends on coordinating decisions across the workflow, not maximizing the utilization of each asset in isolation.
Rockwell’s stack: simulate, orchestrate, move
The press conference organized the production-logistics portfolio into three layers: simulation, orchestration, and movement. Together, these layers indicate how Rockwell intends to differentiate from robot-centric competitors and warehouse-only automation providers.
1. Simulate the operating model
Digital twins can validate layouts, traffic, throughput, safety zones, and control logic before equipment is commissioned. Rockwell also argued that major end users increasingly expect machine builders to provide a digital twin with the physical machine. In production logistics, that model has continuing value because routes, product mixes, cell configurations, and replenishment rules change over the asset lifecycle. A useful digital twin should therefore evolve from a commissioning tool into an operational decision-support asset.
2. Orchestrate work across people and assets
FactoryTalk Orchestration is central to the strategy. Rockwell said customer experience after its AMR acquisition revealed that the real challenge was coordinating robots with carts, people, machines, and software. That observation is directionally correct. Mixed environments will remain the norm for years, and manufacturers need workflow logic that can assign the next best task to an AMR, fixed system, or person while preserving production priorities.
The most compelling orchestration use case is dynamic response. If a supply-chain issue changes raw-material availability, the production schedule, material calls, and execution sequence should adjust together. This requires integration with manufacturing execution and production management systems, not merely fleet management.
3. Move material with the appropriate technology
Rockwell’s movement layer includes AMRs and independent cart technology, supplemented by robotics partners for applications such as palletizing. The portfolio reflects a practical reality: production logistics is not a single-robot category. Different workflows may require mobile transport, precise linear motion, storage and retrieval, or robotic handling. Competitive advantage will depend on coordinating these technologies as one workflow and integrating them to the control layer.
The Twinsburg case shows the value of integration
Rockwell used its Twinsburg, Ohio, plant as the principal proof point. The deployment began with autonomous material movement to reduce manual cart handling. The second phase integrated that capability with FactoryTalk production software, allowing the system to deliver the correct material in the required place, time, amount, and sequence.
According to the presentation, benefits from the first phase appeared in less than a month, while the interval between the first and second phases was approximately four to six months. Rockwell emphasized that workers were reassigned to higher-value plant roles rather than eliminated. The integrated phase reportedly reduced floor-space requirements and work-in-process, creating working-capital benefits in addition to labor-productivity gains.
“As soon as the pilot works, we immediately go to: how do we scale it across our facility?”
The case also illustrates an important adoption pattern. A transport-only pilot can establish safety, reliability, and workforce acceptance quickly. The larger business case emerges when the pilot is connected to production software and scaled across workflows. This is where manufacturers should measure schedule adherence, line starvation, work-in-process, floor-space consumption, indirect labor, and changeover performance, rather than focusing only on robot travel or labor displacement.
Manufacturing and warehousing are converging, but not becoming identical
Rockwell sees growing integration between production lines, adjacent warehouses, automated storage and retrieval systems, and shipping docks. Co-located manufacturing and warehousing make this convergence especially visible: components move from storage to assembly, finished goods move from the line to storage, and production priorities influence downstream handling.
However, Rockwell’s strongest position remains production logistics rather than general e-commerce fulfillment. The company can connect manufacturing software and controls to physical movement, whereas fulfillment specialists often optimize high-volume picking and seasonal labor flexibility. In warehouse environments, Rockwell must also integrate with warehouse management and warehouse execution systems. That makes interoperability, APIs, and ownership of workflow decisions crucial architectural questions.
Truck loading and unloading remain an important boundary. Rockwell described these applications as technically difficult because trailers vary, loads shift, and safety conditions are less controlled. This is a useful reminder that autonomous material flow will advance unevenly. Structured, repeatable movement inside the plant will automate faster than variable dock-edge work.
What manufacturers should do now
Start with a production constraint, not a robot count. Select a workflow where material availability affects throughput, such as line-side replenishment, packaging-material delivery, work-in-process transfer, or finished-goods evacuation. Define the baseline using line-starvation minutes, replenishment response time, indirect travel, and WIP.
Design the integration before the pilot. Document interfaces to MES or production management, ERP, WMS/WES, controls, safety systems, and identity services. A pilot that cannot exchange production status and task priorities may prove navigation but will not prove production value.
Model the mixed environment. Assume people, forklifts, carts, AMRs, conveyors, and fixed automation will coexist. Validate traffic, exceptions, manual recovery, charging, and safe-state behavior using a digital model before scaling.
Use phased economics. Separate phase-one transport savings from phase-two operational gains. The latter may include lower WIP, recovered floor space, better sequence adherence, fewer shortages, and higher OEE. These benefits often justify integration effort more than labor savings alone.
Build change management into commissioning. Create role-specific training for operators, maintenance, supervisors, controls engineers, and IT/OT teams. Define who owns workflow rules, exception handling, fleet availability, cybersecurity, and continuous improvement.
Analyst assessment
Rockwell’s production-logistics message is strategically credible because it aligns with the company’s installed base and its ability to integrate software, controls, motion, and robotics. The acquisition of an AMR platform supplied a visible physical asset, but orchestration is the more consequential layer. If Rockwell can make FactoryTalk Orchestration open enough to coordinate heterogeneous equipment and straightforward enough for plants to deploy repeatedly, it can compete for a broader share of the intralogistics architecture.
Execution risks remain. Manufacturers operate mixed fleets and multiple software systems, so closed or overly Rockwell-centric workflows would limit adoption. Digital-twin value also depends on maintaining models after commissioning, a discipline many plants have not established. Finally, the ROI claims in the transcript include several partially captured figures; buyers should request validated baselines, calculation methods, and comparable references before generalizing the Twinsburg results.
The larger trend is clear: production logistics is moving from an indirect support function toward a software-defined component of plant operations. The winners will not be determined only by the best mobile robot. They will be the suppliers that connect material movement to production intent, manage exceptions across people and machines, and turn successful pilots into repeatable plant-wide operating models.
The post Beyond the AMR: Rockwell’s Production Logistics Strategy Connects Material Flow to Plant Autonomy appeared first on Logistics Viewpoints.
Non classé
Beyond the AMR: Rockwell’s Production Logistics Strategy Connects Material Flow to Plant Autonomy
Published
4 heures agoon
20 novembre 2026By
An analyst perspective on why orchestration, digital twins, and plant-floor integration matter more than the robot alone
Production logistics becomes a control problem
Rockwell Automation’s press conference presented a clear thesis: the next major productivity opportunity lies in the space between automated processes. Many factories have sophisticated machines and well-instrumented production lines, yet material still arrives through manual, disconnected workflows. The result is a familiar contradiction: a highly automated line can still depend on a forklift driver or an operator pushing a cart at its boundary.
“At the end of the line, there was a person driving a forklift and a person pushing a cart.”
That gap is where Rockwell is positioning production logistics. Rather than treating intralogistics as a stand-alone robotics project, the company describes an end-to-end workflow spanning production software, orchestration, controls, autonomous mobile robots, independent cart technology, and human work. This is a stronger industrial proposition than simply adding AMRs to a fleet. It treats the movement of work-in-process, components, packaging, and finished goods as part of the production system itself.
For manufacturers, the implication is significant. Material movement can become event-driven by production demand, quality status, inventory availability, and equipment conditions. The operational objective shifts from “dispatch a robot” to “maintain the production plan.”
From connected operations to autonomous response
Rockwell placed production logistics within a broader progression from connected operations to predictive and increasingly autonomous plants. Its “sense, think, act” framing is familiar in robotics, but the company extends the concept beyond the mobile robot to machines, lines, and plant-level workflows. Sensors establish context, software evaluates conditions, and physical assets execute the response, with a human retained in the loop where risk or uncertainty requires oversight.
“The right product to the right spot at the right time.”
This framing addresses one of the hardest problems in plant automation: local optimization does not automatically create system optimization. A packaging machine can be highly efficient while waiting for film. An assembly cell can meet its cycle time but starve because a component was not replenished in sequence. A warehouse can optimize picks while production priorities have already changed. The value of autonomy therefore depends on coordinating decisions across the workflow, not maximizing the utilization of each asset in isolation.
Rockwell’s stack: simulate, orchestrate, move
The press conference organized the production-logistics portfolio into three layers: simulation, orchestration, and movement. Together, these layers indicate how Rockwell intends to differentiate from robot-centric competitors and warehouse-only automation providers.
1. Simulate the operating model
Digital twins can validate layouts, traffic, throughput, safety zones, and control logic before equipment is commissioned. Rockwell also argued that major end users increasingly expect machine builders to provide a digital twin with the physical machine. In production logistics, that model has continuing value because routes, product mixes, cell configurations, and replenishment rules change over the asset lifecycle. A useful digital twin should therefore evolve from a commissioning tool into an operational decision-support asset.
2. Orchestrate work across people and assets
FactoryTalk Orchestration is central to the strategy. Rockwell said customer experience after its AMR acquisition revealed that the real challenge was coordinating robots with carts, people, machines, and software. That observation is directionally correct. Mixed environments will remain the norm for years, and manufacturers need workflow logic that can assign the next best task to an AMR, fixed system, or person while preserving production priorities.
The most compelling orchestration use case is dynamic response. If a supply-chain issue changes raw-material availability, the production schedule, material calls, and execution sequence should adjust together. This requires integration with manufacturing execution and production management systems, not merely fleet management.
3. Move material with the appropriate technology
Rockwell’s movement layer includes AMRs and independent cart technology, supplemented by robotics partners for applications such as palletizing. The portfolio reflects a practical reality: production logistics is not a single-robot category. Different workflows may require mobile transport, precise linear motion, storage and retrieval, or robotic handling. Competitive advantage will depend on coordinating these technologies as one workflow and integrating them to the control layer.
The Twinsburg case shows the value of integration
Rockwell used its Twinsburg, Ohio, plant as the principal proof point. The deployment began with autonomous material movement to reduce manual cart handling. The second phase integrated that capability with FactoryTalk production software, allowing the system to deliver the correct material in the required place, time, amount, and sequence.
According to the presentation, benefits from the first phase appeared in less than a month, while the interval between the first and second phases was approximately four to six months. Rockwell emphasized that workers were reassigned to higher-value plant roles rather than eliminated. The integrated phase reportedly reduced floor-space requirements and work-in-process, creating working-capital benefits in addition to labor-productivity gains.
“As soon as the pilot works, we immediately go to: how do we scale it across our facility?”
The case also illustrates an important adoption pattern. A transport-only pilot can establish safety, reliability, and workforce acceptance quickly. The larger business case emerges when the pilot is connected to production software and scaled across workflows. This is where manufacturers should measure schedule adherence, line starvation, work-in-process, floor-space consumption, indirect labor, and changeover performance, rather than focusing only on robot travel or labor displacement.
Manufacturing and warehousing are converging, but not becoming identical
Rockwell sees growing integration between production lines, adjacent warehouses, automated storage and retrieval systems, and shipping docks. Co-located manufacturing and warehousing make this convergence especially visible: components move from storage to assembly, finished goods move from the line to storage, and production priorities influence downstream handling.
However, Rockwell’s strongest position remains production logistics rather than general e-commerce fulfillment. The company can connect manufacturing software and controls to physical movement, whereas fulfillment specialists often optimize high-volume picking and seasonal labor flexibility. In warehouse environments, Rockwell must also integrate with warehouse management and warehouse execution systems. That makes interoperability, APIs, and ownership of workflow decisions crucial architectural questions.
Truck loading and unloading remain an important boundary. Rockwell described these applications as technically difficult because trailers vary, loads shift, and safety conditions are less controlled. This is a useful reminder that autonomous material flow will advance unevenly. Structured, repeatable movement inside the plant will automate faster than variable dock-edge work.
What manufacturers should do now
Start with a production constraint, not a robot count. Select a workflow where material availability affects throughput, such as line-side replenishment, packaging-material delivery, work-in-process transfer, or finished-goods evacuation. Define the baseline using line-starvation minutes, replenishment response time, indirect travel, and WIP.
Design the integration before the pilot. Document interfaces to MES or production management, ERP, WMS/WES, controls, safety systems, and identity services. A pilot that cannot exchange production status and task priorities may prove navigation but will not prove production value.
Model the mixed environment. Assume people, forklifts, carts, AMRs, conveyors, and fixed automation will coexist. Validate traffic, exceptions, manual recovery, charging, and safe-state behavior using a digital model before scaling.
Use phased economics. Separate phase-one transport savings from phase-two operational gains. The latter may include lower WIP, recovered floor space, better sequence adherence, fewer shortages, and higher OEE. These benefits often justify integration effort more than labor savings alone.
Build change management into commissioning. Create role-specific training for operators, maintenance, supervisors, controls engineers, and IT/OT teams. Define who owns workflow rules, exception handling, fleet availability, cybersecurity, and continuous improvement.
Analyst assessment
Rockwell’s production-logistics message is strategically credible because it aligns with the company’s installed base and its ability to integrate software, controls, motion, and robotics. The acquisition of an AMR platform supplied a visible physical asset, but orchestration is the more consequential layer. If Rockwell can make FactoryTalk Orchestration open enough to coordinate heterogeneous equipment and straightforward enough for plants to deploy repeatedly, it can compete for a broader share of the intralogistics architecture.
Execution risks remain. Manufacturers operate mixed fleets and multiple software systems, so closed or overly Rockwell-centric workflows would limit adoption. Digital-twin value also depends on maintaining models after commissioning, a discipline many plants have not established. Finally, the ROI claims in the transcript include several partially captured figures; buyers should request validated baselines, calculation methods, and comparable references before generalizing the Twinsburg results.
The larger trend is clear: production logistics is moving from an indirect support function toward a software-defined component of plant operations. The winners will not be determined only by the best mobile robot. They will be the suppliers that connect material movement to production intent, manage exceptions across people and machines, and turn successful pilots into repeatable plant-wide operating models.
The post Beyond the AMR: Rockwell’s Production Logistics Strategy Connects Material Flow to Plant Autonomy appeared first on Logistics Viewpoints.
Non classé
DHL Supply Chain and the End of Peak Season: Can Warehouse Robotics Flex Fast Enough?
Published
5 heures agoon
20 novembre 2026By
For decades, warehouse peak season was something operators could circle on a calendar. Black Friday arrived. Holiday orders surged. Distribution centers added temporary labor, opened extra shifts, increased transportation capacity, and prepared for several frantic weeks before volumes settled back into something resembling normal. That model is becoming considerably less reliable.
Promotions happen more frequently. E-commerce demand can change quickly. Product launches can create sudden volume spikes. Weather, geopolitical disruptions, tariffs, and viral products can alter demand patterns with little warning. For warehouse operators, the challenge is shifting from preparing for the peak to operating in an environment where a peak can appear almost anywhere. That change makes warehouse automation interesting for a reason that has relatively little to do with eliminating labor. The more important question may be: Can automation give a warehouse capacity exactly when it needs it?
DHL Supply Chain Offers an Interesting Test
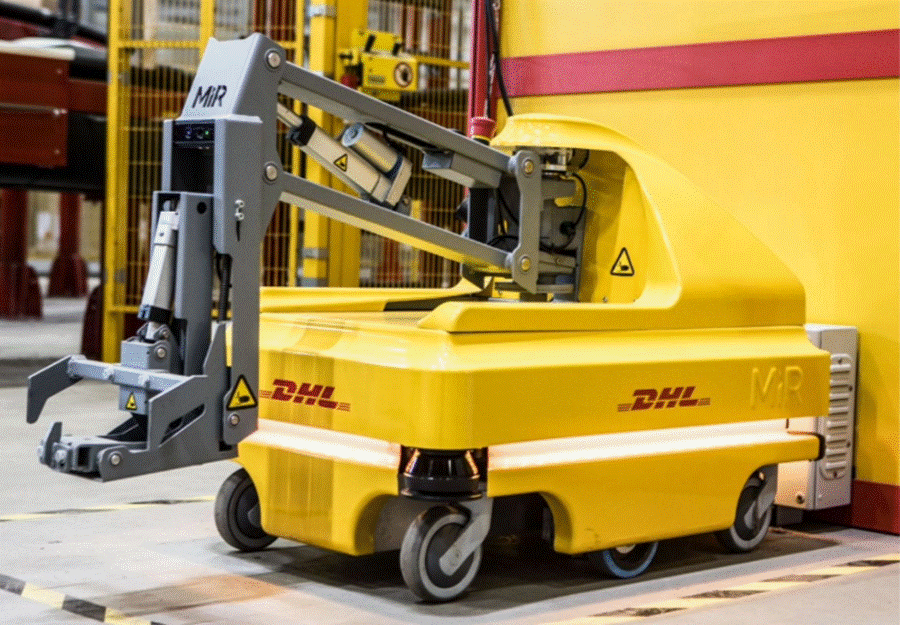
A recent article from DHL Supply Chain provides a useful example. The company says it operates more than 9,000 collaborative robots globally, after adding roughly 1,000 units during the previous year. More interestingly, DHL says it can temporarily expand its active robot fleet by approximately 30 percent during peak periods. Its robotic systems have also supported more than 1.5 billion item picks. That 30 percent figure deserves attention.
Traditional warehouse automation economics have often been built around relatively stable throughput assumptions. A conveyor, sorter, or large AS/RS may produce tremendous productivity, but operators generally cannot add 30 percent more conveyor for November and remove it in January. Mobile robotics changes that calculation. If additional robots can be deployed temporarily, operators can begin treating automated capacity somewhat more like seasonal labor: bring it in when volumes rise, reduce it when demand falls. That is potentially a major change in warehouse economics.
The Biggest Automation Users Still Have an Advantage
There is, however, an important caveat. Scale matters. Recent research from Link Logistics estimates that only around 6 percent of North American warehouses are highly automated, while approximately 63 percent remain fully manual and another 31 percent have some degree of partial automation. The research also identifies Amazon and Walmart as the two largest deployers of warehouse robotics in the United States. Amazon had deployed more than one million robots across its fulfillment operations by mid-2025, according to the research. Meanwhile, Walmart reports that roughly 60 percent of its stores receive merchandise from automated distribution centers and more than half of its fulfillment-center volume moves through automated systems.
Those numbers demonstrate what automation can accomplish at extraordinary scale. But most warehouses are not Amazon warehouses. That distinction is important because the next phase of warehouse automation adoption will depend less on proving robotics works and more on proving that the economics work for operators with fewer facilities, lower throughput, shorter customer contracts, and greater SKU variability.
From Maximum Throughput to Flexible Throughput
Warehouse automation suppliers have traditionally competed on measures such as picks per hour, storage density, labor reduction, accuracy, and maximum throughput. Those measures remain important. But another metric deserves a place on the automation scorecard: How quickly can capacity be added or removed?
Imagine two warehouses capable of processing 20,000 orders per day. Warehouse A can reach 30,000 orders, but doing so requires designing permanent automation around peak capacity. Warehouse B normally operates at 20,000 but can add robots, shifts, or automated workcells when volume jumps. The first operation may offer superior theoretical throughput. The second could potentially offer better economics if demand is volatile. That makes utilization especially important. An expensive automation system producing impressive performance for six weeks but running well below capacity for the other 46 weeks may not deliver the return suggested by peak-season numbers. Flexible robotics begins to change that equation.
Software Becomes Part of the Capacity Question
Adding robots is only useful if the warehouse can coordinate them. This is why orchestration, WMS integration, labor management, and real-time decision-making are becoming more central to automation strategy. Recent research expects AI-based warehouse systems increasingly to coordinate conveyors, picking systems, mobile robots, and other resources rather than simply optimize individual machines. That means tomorrow’s warehouse automation competition may not simply be robot versus robot. It could increasingly be about how quickly the entire operation can rebalance itself.
If 50 additional AMRs arrive for a seasonal surge, can the WMS allocate work effectively? Can charging infrastructure support them? Can workers be trained quickly? Do picking stations become the new bottleneck? Can outbound sortation handle the additional volume? Adding robotic capacity to one process while starving another simply moves the queue.
The New Peak-Season ROI Question
Warehouse executives evaluating automation should therefore ask vendors questions that extend beyond equipment specifications:
How much additional capacity can I activate during a demand spike?
How quickly can that capacity be deployed?
What happens to utilization during slower months?
Where does the next operational bottleneck appear?
What additional labor is required as robotic capacity increases?
What software, charging, networking, or workstation investments are necessary?
Can capacity move between facilities?
These questions shift automation ROI from “How many people can this technology replace?” toward “How economically can this operation respond to demand?” That is a much more useful discussion.
Takeaway
Warehouse automation is moving beyond a simple labor-substitution story. Amazon and Walmart demonstrate what automation can achieve at enormous scale, while DHL Supply Chain’s ability to expand its active robot fleet during peak periods points toward another potentially important model: automation as elastic operating capacity. For warehouse operators, that distinction matters.
The best automated warehouse may not be the facility with the most robots, the highest theoretical throughput, or even the smallest workforce. It may be the warehouse that can absorb tomorrow’s unexpected volume without having to redesign today’s operation. And in a supply chain where peak season increasingly refuses to stay on the calendar, flexibility itself may become one of automation’s most valuable returns.
The post DHL Supply Chain and the End of Peak Season: Can Warehouse Robotics Flex Fast Enough? appeared first on Logistics Viewpoints.


Beyond the AMR: Rockwell’s Production Logistics Strategy Connects Material Flow to Plant Autonomy
Beyond the AMR: Rockwell’s Production Logistics Strategy Connects Material Flow to Plant Autonomy
DHL Supply Chain and the End of Peak Season: Can Warehouse Robotics Flex Fast Enough?
Freightos Global Freight Outlook – September 2026
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update

Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
Trending
- Non classé3 mois ago
Freightos Global Freight Outlook – September 2026
- Non classé4 mois ago
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update
-
 Non classé2 ans ago
Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
-
 Non classé7 mois ago
Why Sulfuric Acid Is Emerging as a Supply Chain Constraint in Copper
- Non classé6 mois ago
Container rates starting to spike on peak season rush – June 2, 2026 Update
- Non classé1 an ago
13 Books Logistics And Supply Chain Experts Need To Read
- Non classé1 an ago
Ex-Asia ocean rates climb on GRIs, despite slowing demand – October 22, 2025 Update
- Non classé5 mois ago
LCL Shipping Cost Calculator: Calculate Air and Sea Shipping Freight Rates