Non classé
From Microgrids to Hypergrids: Data Center Power Demands + Hyperscaler Capital is Creating a New Grid Architecture

Published
11 mois agoon
By
About 0.3 percent of US power was generated by microgrids in 2024, but data centers use about 4.4 percent of US power today, a figure expected to grow to about 12 percent by 2030. The urgent rush to develop new and more capable “frontier models,” which are critical to the functioning of AI applications, is viewed as an existential requirement for hyperscalers and is inherently linked to enormous energy consumption. These models are developed using power-hungry machine learning algorithms that run on graphics processing units (GPUs), tensor processing units (TPUs), and conventional central processing units (CPUs).
The power required to create these frontier models has become a limiting factor for hyperscalers seeking to remain relevant and competitive, driving them to increasingly act as their own utilities. Traditionally, data centers sourced power from utilities, but new hyperscale data centers are unwilling to wait through five-plus-year planning cycles to access grid power. For example, the Stargate data center currently under construction is planned for a power consumption of 1.2 GW at its flagship site in Abilene, Texas. Stargate is a portfolio of massive sites designed to reach a total commitment of 10 GW and $500 billion in investment across the US.
Crusoe Energy is building these data centers and is actively developing the power plants and underlying infrastructure required to support the initiative at the flagship Abilene campus. In this effort, Crusoe is acting as a vertically integrated AI infrastructure provider, handling both the power generation and the data center build.
The Hypergrid Regulation Problem
The regulation of microgrids has been problematic. FERC Order No. 2023 (issued July 2023) has helped reduce connection queues for new power sources by introducing the Cluster Study Process, the “First-Ready, First-Served” reform, and firm deadlines for grid operators to complete studies, including financial penalties for failure to process requests on time. FERC Order No. 2023 deals exclusively with the generator interconnection queue and applies to new gas and nuclear power plants, as well as renewables such as wind and solar and energy storage.
Historically, a data center’s primary function has been to act as a massive consumer (load) of electricity. Connecting a load, such as a factory or data center, has traditionally fallen under the authority of state public utility commissions (PUCs), not FERC. Because Order No. 2023 addresses only generator queues, it provides no relief for load interconnection queues, which are the primary source of the multiyear delays faced by data centers.
If a data center’s microgrid meets the regulatory requirements to sell power (export) to the wholesale interstate grid—for example, by qualifying as a Qualifying Facility or Exempt Wholesale Generator—the interconnection of that specific generating asset would be governed by FERC’s generator interconnection procedures, including the 2023 reforms. However, data centers can simultaneously be large loads, making them subject to state utility regulation as well as certain federal approvals.
The US Department of Energy (DOE) has formally urged FERC to initiate rulemaking to clarify federal jurisdiction and establish standardized rules for the interconnection of large electrical loads, typically defined as greater than 20 MW and including data centers. However, the jurisdictional boundary between state and federal authority remains unsettled as of the end of 2025.
The Hypergrid Interconnection Problem
In principle, utilities welcome additional business and the opportunity to sell power to data centers, but hyperscalers are not typical grid customers. In the current frenzied rush to build data centers, utilities are not prepared to meet the aggressive schedules that data center customers demand.
The Stargate project is a massive joint-venture data center complex involving OpenAI, Oracle, and SoftBank. The project relies on Crusoe to address the primary bottleneck facing new hyperscale AI data centers: the speed and availability of power. Crusoe is the developer and operator of Stargate’s flagship campus in Abilene, Texas, which is planned to scale up to 1.2 GW of power capacity. Crusoe’s core business model is to control the full stack, from power generation and energy procurement to data center design and hardware deployment, enabling sites to come online in months rather than years.
Bridge Power: For the Abilene site, Crusoe is installing GE Vernova LM2500XPRESS aeroderivative gas turbines. This on-site natural gas plant is a crucial component that allows the data center to energize quickly, bypassing slow utility interconnection queues. These units are flexible, highly efficient, and capable of providing nearly 1 GW of power.
Renewable Integration: The Abilene site is also strategically located to draw on the region’s abundant wind power, a key factor in Crusoe’s site selection, and uses large-scale behind-the-meter battery storage and solar resources.
Backup/Resilience: The gas turbines function as a highly responsive source of backup power for the data halls, replacing traditional, less efficient diesel generators and ensuring 24/7 reliability for highly sensitive AI workload.
Future Plans: Crusoe has announced a long-term strategic partnership with Blue Energy to develop a massive, multi-gigawatt, nuclear-powered data center campus at the Port of Victoria, Texas, demonstrating its commitment to pioneering long-term, high-capacity generation solutions.
In short, Crusoe is not just building a building; it is building a Grid-Interactive Compute Plant (GICP)—a massive power generation and orchestration asset designed to serve the Stargate project’s unprecedented energy demands.
Stargate Data Center (Crusoe Energy)
The Utility Perspective on Power for Data Centers
Utilities have several key performance indicators that help them maintain reliable power, and they will assess whether a hypergrid improves or degrades these metrics. The electric grid (macrogrid) is designed to always have more power available than is being used at any given moment. This “excess generating capacity” is best measured by the Planning Reserve Margin (PRM). The reserve margin represents the amount of available generating capacity a region has above its anticipated peak demand.
The industry standard minimum target for reserve margin across most US regions has historically been around 15 percent. This reserve is intended to protect against long-duration outages. Spinning reserve, used for frequency regulation, is approximately 3 to 7 percent and can be deployed within seconds to help regulate grid frequency.
Both reserve margin and spinning reserves are threatened by massive new loads. With advanced grid control systems, hypergrids can be designed to improve both reserve and spinning margins.
Conclusion and Outlook
In recent years in the US, non-dispatchable wind and solar power have dominated new power additions, but this new capacity has not kept pace with rising power demand, and both reserve margins and spinning reserves have declined. This is due in part to the retirement of generation assets such as steam turbines in coal and nuclear plants, as well as older gas generators. Advanced grid-forming inverters for solar PV and battery systems, along with advanced power converters for wind turbines and Static VAR Compensators (SVCs) and STATCOMs, can provide synthetic inertia and voltage regulation capabilities. While renewable power is not dispatchable, large grid-scale batteries are, and these batteries will play an increasingly important role for data centers, far beyond the function that traditional data center UPS systems served in the past.
Given the current crisis of rapidly rising data center power loads, aging infrastructure, and retiring firm generation, the most effective path to a more reliable grid requires new hypergrids to focus on advanced automation, grid-forming inverters, expanded battery storage, more effective demand response, and a more interconnected and digital grid.
Regulations for connecting hypergrids and microgrids to local macrogrids need to be improved through consistent rules that reduce connection queues without compromising grid stability or reliability. The split authority—where FERC regulates how power generation is added to the grid while state public utility commissions regulate how new loads are added—was established before microgrids were common. Today, the massive scale of hypergrids is placing significant pressure on these outdated regulatory structures. The US should strive to be more highly interconnected across North America to improve the effective reserve margin.
Ultimately, whether it is a 1 MW microgrid or a 700 MW hypergrid, designing these systems with advanced control technologies that enhance grid stability when connected to the macrogrid, while also meeting load requirements in island mode, would significantly ease interconnection. Both microgrids and hypergrids share these requirements:
The Core Requirements
Protection and isolation (safety).
Limit harmonic distortion and voltage flicker.
Capability to absorb or inject reactive power (VARs) during both power import and export.
Advanced Requirements
The microgrid/hypergrid BESS and PV inverters should be capable of providing rapid, advanced voltage support to the utility’s distribution system, effectively acting as a high-speed STATCOM (Static Synchronous Compensator).
The microgrid/hypergrid should be able to modulate its real power output (MW) very quickly to participate in frequency regulation markets.
Microgrids/hypergrids should have black start capability.
The microgrid/hypergrid must contractually offer spare capacity and BESS to participate in the utility’s demand response or virtual power plant (VPP) programs, agreeing to inject power or curtail load when the macrogrid is stressed.
Microgrids/hypergrids need to demonstrate that their advanced inverter controls are sophisticated enough to mimic the stabilizing effect of physical inertia, preventing severe frequency drops when a large generator trips offline.
Where smaller microgrids typically relied on a mix of intermittent renewables (solar PV and wind), modest battery energy storage systems, and smaller, high-speed reciprocating diesel or gas engines for backup during island mode, hypergrids are defined by their sheer scale. These massive facilities integrate gigawatt-class gas turbines or large, modular fuel cell arrays alongside industrial-scale UPS systems and grid-scale BESS measured in tens or hundreds of megawatts (MW). The mission has shifted: traditional microgrids required a grid connection primarily to offload excess renewable generation that exceeded local load, whereas hypergrids are architected to become active partners in grid management, with significant potential to provide high-value grid services, including large-scale demand response (DR), frequency regulation, and dynamic voltage support through controlled injection and absorption of reactive power (VARs). In doing so, they transform the data center from a massive load into a dispatchable, revenue-generating asset.
Hyperscalers (Microsoft, Google, Amazon, Meta) continue to maintain ambitious public goals, such as achieving 100 percent renewable energy, yet many hypergrids are currently powered by natural gas. Hyperscalers are not abandoning their renewable commitments, but they are prioritizing “speed to power” over “immediacy of green power,” creating a significant and visible contradiction. They are not simply building gas plants; they are designing transitional, future-proof energy platforms in which the current reliance on natural gas is a deliberate, temporary step to address the speed-to-power constraint. This contradiction is driving a new hypergrid design philosophy centered on modularity, fuel flexibility, and long-term site viability for clean energy integration.
Hyperscalers are specifying natural gas turbines, often aeroderivative models, that are manufactured to be hydrogen-ready. Hypergrids are deploying BESS systems far larger than required for basic UPS backup. Power-first site selection has become a priority, and hyperscalers, together with their utility partners, are explicitly designing the hypergrid as a multi-phase energy complex intended to ultimately transition away from gas toward firm, zero-carbon energy sources. Site selection is based not only on available land, but also on access to underutilized high-voltage transmission lines or proximity to existing clean energy assets, such as retiring coal plants with established interconnection rights.
In summary, the hypergrid replaces the passive relationship characteristic of traditional microgrids with an active, contractual partnership with the utility, transforming a potentially disruptive massive load into a system-stabilizing asset. If designed correctly, hypergrids can reduce power costs and improve the reliability of the macrogrid on which everyone depends.
F
The post From Microgrids to Hypergrids: Data Center Power Demands + Hyperscaler Capital is Creating a New Grid Architecture appeared first on Logistics Viewpoints.
You may like
Non classé
The Systems-Engineered Logistics Operation: From Transformation Projects to Continuous Design
Published
17 heures agoon
3 novembre 2026By
For years, logistics transformation has been organized as a succession of projects. Implement the platform. Build the control tower. Automate the facility. Add the AI layer. The problem is that logistics no longer changes on a project cadence.
That environment is disappearing. The future logistics will need to be designed continuously. The Autonomous Logistics Network is one expression of this end state, but reaching it requires continuous design rather than a one-time transformation project.
Stop Thinking in Technology Stacks
Modern logistics networks are becoming integrated combinations of physical assets, software, data, optimization, AI, robotics, people, partners, and automated decisions. Calling this a technology stack understates what is happening.
It is an operating system. The important design questions are no longer confined to which applications a company owns. Leaders have to consider how decisions flow, how data maintain continuity across systems, how automation interacts with people, how models are governed, how exceptions escalate, and how the organization behaves when components fail.
That is systems engineering territory. The companies that manage this architecture deliberately will have an advantage over those that continue adding capabilities one project at a time.
Intelligence Is Moving to the Point of Action
Logistics technology is moving from systems of record toward systems of decision. Traditional applications captured transactions and supported workflows. Analytical systems added prediction and optimization. The emerging layer increasingly combines real-time signals, AI, optimization, agents, and execution connectivity.
The result is intelligence closer to the point of action. A shipment delay can be identified, its impact evaluated, alternatives generated, and a response executed with limited human intervention. Transportation systems can continuously re-evaluate routes, capacity, and exceptions instead of waiting for manual replanning. Warehouse and yard systems can adjust priorities as conditions change.
This will make logistics faster. It will also make architecture and governance more consequential.
When software only reported information, a bad output could be ignored. When software acts, the operating envelope matters.
Human Work Moves Up the Decision Stack
More automation does not eliminate the human role. It changes it.
People will spend less time collecting information, reconciling spreadsheets, monitoring routine transactions, and making repetitive bounded decisions. They will spend more time dealing with novel exceptions, cross-functional tradeoffs, strategic choices, carrier and customer relationships, system design, and governance.
That is a better use of human capability. It is also a harder job.
The future planner, transportation manager, warehouse leader, or logistics executive will need to understand not only operations but the automated systems influencing operations. They will need to know when to trust a recommendation, when to challenge it, and how a decision in one part of the system affects another. Logistics expertise will become more architectural.
Continuous Design Requires Continuous Validation
If the system changes continuously, validation must become continuous as well.
AI models drift. Business priorities change. automation rules evolve. New interfaces are added. Local process changes accumulate. External conditions move.
The organization cannot wait for the next transformation program to determine whether the operating system still meets its requirements. Performance, model behavior, exception patterns, overrides, decision latency, data quality, and failure modes will need ongoing monitoring.
This creates a closed lifecycle: design, deploy, observe, validate, improve, and redesign. Transformation becomes less of an event and more of a management discipline.
Resilience Becomes an Architectural Property
The future of resilience is also likely to move beyond static buffers. Inventory and redundancy will remain important, but digital systems will make logistics more capable of sensing, simulating, and responding dynamically.
A disruption can trigger scenario analysis. A digital twin can estimate consequences. Optimization can evaluate alternatives. AI can interpret unstructured signals. Automated decision systems can act inside approved boundaries.
This does not eliminate the need for physical resilience. It allows physical resilience and decision resilience to work together.
The strongest logistics networks will not simply carry more protection. They will understand their dependencies and reconfigure faster when conditions change.
Architecture Becomes a Competitive Capability
For years, companies differentiated logistics through network scale, facility and transportation assets, carrier leverage, operational excellence, service design, and technology investment. Architecture is becoming another source of advantage.
Two companies may use similar software and still achieve very different results because one has better process integration, clearer decision rights, stronger data, more effective automation boundaries, better failure recovery, and tighter governance. The advantage does not come from owning the component. It comes from how the components have been engineered to work together.
Logistics Management Becomes Systems Management
That may be the larger lesson of this series. Logistics networks are already systems of systems. The technology is making them more connected, more autonomous, and more adaptive. That complexity cannot be managed indefinitely through functional optimization and periodic implementation projects.
The discipline has to evolve.
Define requirements before selecting solutions. Design the operating model. Architect processes, data, and decisions together. Engineer technology into the system rather than around it. Validate the outcome. Govern change. Design for failure. Improve continuously.
The competitive advantage will not come from owning the same AI, automation, TMS, WMS, visibility, and execution technologies everybody else can buy. It will come from how coherently those components have been engineered to work together. The future of logistics management is not simply more digital, more autonomous, or more intelligent. It is more engineered.
Related Logistics Viewpoints research
Systems Engineering in Logistics
The New Architecture of Logistics
2026 Supply Chain Decision Intelligence Market Map
Digital Transformation in Logistics
Previous in this series: Design for Failure: Resilience, Risk, and Failure Modes
Request the Systems Engineering in Logistics Client Edition
If your organization is evaluating a logistics transformation, technology strategy, automation program, or operating-model redesign, I would be glad to provide the complete client edition and discuss how the framework applies to your priorities, constraints, and operating environment.
The post The Systems-Engineered Logistics Operation: From Transformation Projects to Continuous Design appeared first on Logistics Viewpoints.
Non classé
Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy
Published
17 heures agoon
3 novembre 2026By
Warehouse automation has traditionally been discussed one facility at a time. A retailer installs an automated storage system, deploys mobile robots, adds robotic picking, or upgrades sortation. The business case is then measured against improvements within that particular building. Walmart and Symbotic are beginning to challenge that way of thinking.
On October 29, Walmart and Symbotic announced an expanded commercial agreement that will bring additional automation capabilities to 25 U.S. regional distribution centers. The agreement includes an initial commitment of approximately $6 billion, covering work over several years and multiple locations. Walmart says the initiative is intended to support upstream e-commerce inventory management, increase storage capacity, and improve the movement of products through its supply chain. Those numbers make the announcement noteworthy. But the more interesting story is what the scale of the commitment says about the next phase of warehouse automation.
From an Automation Project to an Operating Model
For years, warehouse automation investments were frequently justified around specific bottlenecks: reduced picker travel, increase storage density, improve sortation throughput, or offset labor requirements. Those are still important objectives. But Walmart is evaluating automation against something larger: the performance of an interconnected distribution network supporting stores, pickup and home delivery.
Rob Montgomery, executive vice president for Walmart U.S. Supply Chain Operations, tied the expanded agreement to improving service, growing capacity, simplifying work for associates and lowering costs. The company also expects the expansion to support broader assortment, greater speed and more reliable replenishment. That distinction matters.
Warehouse automation increasingly needs to be evaluated not simply by asking, “How much faster can this facility pick?” but by asking, “What does this investment change across the supply chain?” Does additional storage capacity improve inventory positioning? Does automation enable later ordering cutoffs? Can replenishment become more predictable? Can the same technology architecture be repeated across multiple facilities without redesigning the operation every time? Those questions take warehouse automation discussions much closer to business strategy.
Scale Is Becoming Part of the Business Case
The Walmart-Symbotic relationship is particularly interesting because this is not a new pilot. Reuters reported that Symbotic has been helping automate Walmart’s supply chain since 2017, while the latest agreement extends automation to another 25 regional distribution centers. There is another layer to the expansion as well. Supply Chain Dive reported that Walmart committed an additional $125 million toward research and development of racking technology and related picking, process-flow and inventory-management capabilities. That is important because it suggests the competitive discussion is moving beyond individual pieces of robotic hardware. Warehouse automation is increasingly about how storage, picking, inventory, material movement and software operate together.
Symbotic’s current portfolio illustrates that evolution. The company says its integrated offering includes BreakPack for each-picking and SymMicro for e-commerce micro-fulfillment, supported by proprietary software that uses AI to orchestrate product movement. The question for warehouse operators, therefore, becomes less about which robot performs an individual task and more about how multiple automation layers combine into a repeatable operating system.
Walmart Is Not the Only Signal
Developments elsewhere reinforce the same trend. Amazon reported in 2026 that it has deployed more than one million robots across its operations network. Its systems now span inventory handling, mobile robotics, robotic arms and packaging automation. The company also says its Sequoia system can identify and store inventory up to 75 percent faster at fulfillment centers.
Meanwhile, DHL Supply Chain and Locus Robotics reached another useful measure of scale in 2026: one billion warehouse picks using Locus AMRs. Locus says thousands of its robots now operate across more than 40 DHL-managed sites worldwide. These examples are different applications with different economics. That is precisely the point. The warehouse automation market is moving beyond the question of whether robotics can work. Leading operators are increasingly confronting the harder questions of where automation should be deployed, how quickly it can scale, how well it integrates with existing operations, and whether benefits survive replication across a network.
The Metrics That Matter After Go-Live
The risk in covering a $6 billion automation agreement is treating announced spending as though it were demonstrated return. It is not. The more valuable story will develop as the systems go live. The measures worth watching include throughput, storage utilization, replenishment performance, labor productivity, system availability, fulfillment speed, implementation cost and the ability to maintain performance during demand peaks. That distinction should matter to technology buyers. A compelling demonstration can show what automation can do. A network-scale deployment begins to show whether the technology can generate similar value repeatedly under different facility and operating conditions. For Walmart, that makes the 25 distribution centers as important as the $6 billion headline.
Takeaway
The next chapter of warehouse automation will not be defined simply by more robots. It will be defined by whether operators can turn automation into a repeatable, measurable and scalable operating capability.
Walmart’s expanded relationship with Symbotic provides an unusually large test of that idea. The announced objectives are ambitious: more capacity, faster product movement, better replenishment, broader assortment, simpler work and lower costs. Now comes the more important part: measuring what changes when those systems are operating across the network. For other warehouse operators considering automation, that may ultimately be the most useful lesson from Walmart. Do not evaluate the robot alone. Evaluate what the automation changes in the economics and performance of the supply chain around it.
The post Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy appeared first on Logistics Viewpoints.
Non classé
Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy
Published
17 heures agoon
3 novembre 2026By
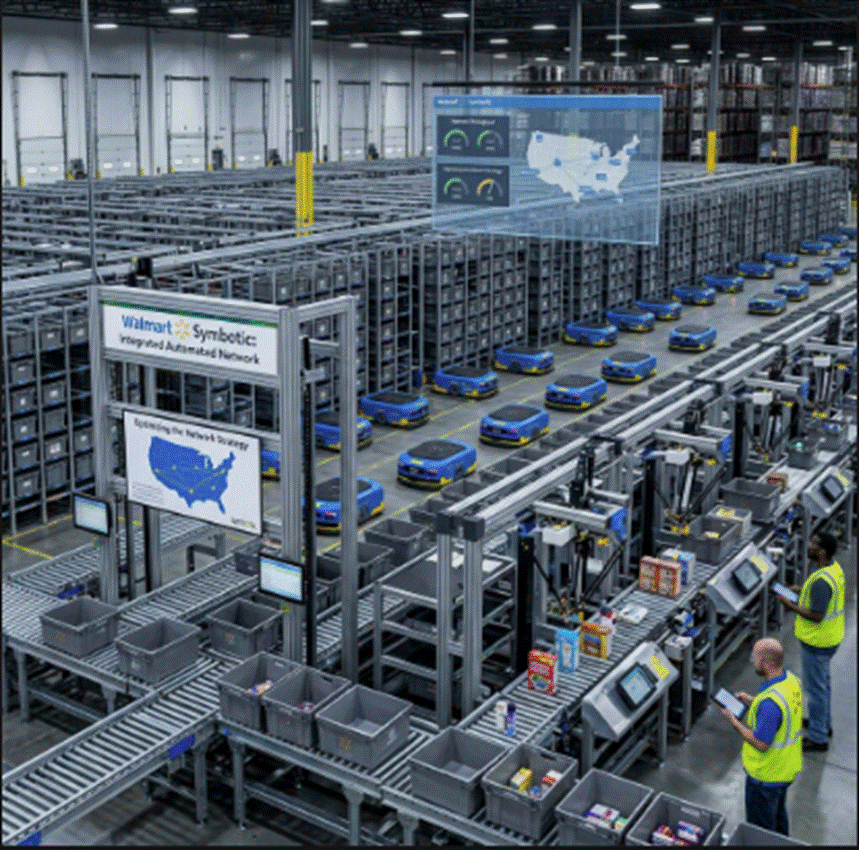
Warehouse automation has traditionally been discussed one facility at a time. A retailer installs an automated storage system, deploys mobile robots, adds robotic picking, or upgrades sortation. The business case is then measured against improvements within that particular building. Walmart and Symbotic are beginning to challenge that way of thinking.
On October 29, Walmart and Symbotic announced an expanded commercial agreement that will bring additional automation capabilities to 25 U.S. regional distribution centers. The agreement includes an initial commitment of approximately $6 billion, covering work over several years and multiple locations. Walmart says the initiative is intended to support upstream e-commerce inventory management, increase storage capacity, and improve the movement of products through its supply chain. Those numbers make the announcement noteworthy. But the more interesting story is what the scale of the commitment says about the next phase of warehouse automation.
From an Automation Project to an Operating Model
For years, warehouse automation investments were frequently justified around specific bottlenecks: reduced picker travel, increase storage density, improve sortation throughput, or offset labor requirements. Those are still important objectives. But Walmart is evaluating automation against something larger: the performance of an interconnected distribution network supporting stores, pickup and home delivery.
Rob Montgomery, executive vice president for Walmart U.S. Supply Chain Operations, tied the expanded agreement to improving service, growing capacity, simplifying work for associates and lowering costs. The company also expects the expansion to support broader assortment, greater speed and more reliable replenishment. That distinction matters.
Warehouse automation increasingly needs to be evaluated not simply by asking, “How much faster can this facility pick?” but by asking, “What does this investment change across the supply chain?” Does additional storage capacity improve inventory positioning? Does automation enable later ordering cutoffs? Can replenishment become more predictable? Can the same technology architecture be repeated across multiple facilities without redesigning the operation every time? Those questions take warehouse automation discussions much closer to business strategy.
Scale Is Becoming Part of the Business Case
The Walmart-Symbotic relationship is particularly interesting because this is not a new pilot. Reuters reported that Symbotic has been helping automate Walmart’s supply chain since 2017, while the latest agreement extends automation to another 25 regional distribution centers. There is another layer to the expansion as well. Supply Chain Dive reported that Walmart committed an additional $125 million toward research and development of racking technology and related picking, process-flow and inventory-management capabilities. That is important because it suggests the competitive discussion is moving beyond individual pieces of robotic hardware. Warehouse automation is increasingly about how storage, picking, inventory, material movement and software operate together.
Symbotic’s current portfolio illustrates that evolution. The company says its integrated offering includes BreakPack for each-picking and SymMicro for e-commerce micro-fulfillment, supported by proprietary software that uses AI to orchestrate product movement. The question for warehouse operators, therefore, becomes less about which robot performs an individual task and more about how multiple automation layers combine into a repeatable operating system.
Walmart Is Not the Only Signal
Developments elsewhere reinforce the same trend. Amazon reported in 2026 that it has deployed more than one million robots across its operations network. Its systems now span inventory handling, mobile robotics, robotic arms and packaging automation. The company also says its Sequoia system can identify and store inventory up to 75 percent faster at fulfillment centers.
Meanwhile, DHL Supply Chain and Locus Robotics reached another useful measure of scale in 2026: one billion warehouse picks using Locus AMRs. Locus says thousands of its robots now operate across more than 40 DHL-managed sites worldwide. These examples are different applications with different economics. That is precisely the point. The warehouse automation market is moving beyond the question of whether robotics can work. Leading operators are increasingly confronting the harder questions of where automation should be deployed, how quickly it can scale, how well it integrates with existing operations, and whether benefits survive replication across a network.
The Metrics That Matter After Go-Live
The risk in covering a $6 billion automation agreement is treating announced spending as though it were demonstrated return. It is not. The more valuable story will develop as the systems go live. The measures worth watching include throughput, storage utilization, replenishment performance, labor productivity, system availability, fulfillment speed, implementation cost and the ability to maintain performance during demand peaks. That distinction should matter to technology buyers. A compelling demonstration can show what automation can do. A network-scale deployment begins to show whether the technology can generate similar value repeatedly under different facility and operating conditions. For Walmart, that makes the 25 distribution centers as important as the $6 billion headline.
Takeaway
The next chapter of warehouse automation will not be defined simply by more robots. It will be defined by whether operators can turn automation into a repeatable, measurable and scalable operating capability.
Walmart’s expanded relationship with Symbotic provides an unusually large test of that idea. The announced objectives are ambitious: more capacity, faster product movement, better replenishment, broader assortment, simpler work and lower costs. Now comes the more important part: measuring what changes when those systems are operating across the network. For other warehouse operators considering automation, that may ultimately be the most useful lesson from Walmart. Do not evaluate the robot alone. Evaluate what the automation changes in the economics and performance of the supply chain around it.
The post Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy appeared first on Logistics Viewpoints.

The Systems-Engineered Logistics Operation: From Transformation Projects to Continuous Design
Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy
Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy
Freightos Global Freight Outlook – September 2026
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update

Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
Trending
- Non classé2 mois ago
Freightos Global Freight Outlook – September 2026
- Non classé4 mois ago
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update
-
 Non classé2 ans ago
Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
-
 Non classé7 mois ago
Why Sulfuric Acid Is Emerging as a Supply Chain Constraint in Copper
- Non classé5 mois ago
Container rates starting to spike on peak season rush – June 2, 2026 Update
- Non classé1 an ago
13 Books Logistics And Supply Chain Experts Need To Read
- Non classé1 an ago
Ex-Asia ocean rates climb on GRIs, despite slowing demand – October 22, 2025 Update
- Non classé4 mois ago
LCL Shipping Cost Calculator: Calculate Air and Sea Shipping Freight Rates