Non classé
Manhattan Associates’ Strategic Vision – Unifying Platforms Integrating AI and Leading the Future

Published
1 an agoon
By
At this year’s keynote, Manhattan Associates outlined its current strategic direction, underscoring platform unification, AI integration, and leadership transition. The presentations provided a clear account of the company’s continued investment in product development and operational capabilities, alongside practical use cases from customer deployments.
Leadership Transition and Strategic Continuity
Eddie Capel, Chairman of the Board
Eddie Capel, Chairman of the Board opened the event by reaffirming Manhattan Associates’ ongoing focus on innovation, partnership, and adaptability. His comments reflected a long-term orientation: technology and strategy are expected to evolve in parallel with shifts in the global supply chain environment. Capel’s remarks highlighted the need for organizations to remain operationally synchronized—across systems, partners, and functions.
He emphasized that tools must speak the same language to support efficient, intelligent operations. Capel also referenced the increasing importance of modular, interoperable systems and the company’s work to reduce friction across supply chain processes. His introduction of Eric Clark as the incoming President and CEO framed the leadership change as an extension of Manhattan’s current trajectory rather than a pivot.
Eric Clark: Emphasis on People, Platform, and Market Responsiveness
Eric Clark, President & CEO
Eric Clark, President & CEO opened by acknowledging the legacy of the organization and thanking Eddie Capel and the broader team for their support. He explained that his decision to join Manhattan was shaped by three main factors: the quality and depth of the team, the pace of platform innovation, and the resilience of the customer community. In his view, these components form the foundation for long-term operational and commercial success.
Clark cited the Manhattan Active Platform as a differentiated asset in the enterprise technology market. Built as a unified suite rather than integrated point solutions, the platform includes end-to-end functionality across supply chain execution, commerce, and planning. He stressed the strategic advantage of managing all functions on a single codebase, which allows for faster updates, stronger data integration, and reduced implementation complexity.
Recent examples included the rollout of a new inventory planning application and the introduction of a hybrid AI-powered demand forecasting engine. Clark noted that these developments were designed to meet emerging customer needs, particularly in markets experiencing unpredictable demand and inventory constraints.
He also introduced the company’s new agentic AI strategy—referring to intelligent software agents that can make autonomous decisions and manage specific operational tasks. According to Clark, these agents are being deployed to reduce manual intervention and enable more adaptive, responsive systems in real-time environments.
Brian Kinsella: Practical Application of Platform Unification
Brian Kinsella, Senior Vice President, Product Management
Brian Kinsella, Senior Vice President, Product Management, focused on the measurable outcomes associated with unified applications. He reported that over 25 customers are currently moving toward unified supply chain execution—leveraging consistent data models, processes, and system behaviors across distribution, transportation, and fulfillment functions.
Kinsella detailed recent functionality developed to support these goals. Examples included dynamic trailer door assignments, shipment planning enhancements, drag-and-drop yard visualization tools, and integrated labor planning modules. Each feature was tied to a larger goal: removing operational silos and enabling system-wide coordination.
He introduced a new solution called Enterprise Promise and Fulfill, built to address enterprise-wide inventory visibility and order fulfillment orchestration. Unlike traditional order management systems, this application incorporates live data from across the network and supports multi-node order allocation and dynamic lead time calculation.
Kinsella also stressed that unification is not only a design goal but a practical enabler of speed, accuracy, and efficiency for customers seeking to simplify multi-system architectures.
Sanjeev Siotia: AI Agents and System Architecture
Sanjeev Siotia, Executive Vice President & CTO
Sanjeev Siotia, Executive Vice President & CTO, provided a technical update on the Manhattan Active Platform. He explained how the company’s API-first, microservices-based architecture serves as the basis for current and future enhancements. Each service operates independently while integrating seamlessly, allowing for more resilient deployments and easier scaling.
Siotia introduced the concept of agentic AI in greater detail. These agents are software entities powered by large language models, capable of coordinating tasks, making decisions, and adapting in real time based on context. This capability marks a shift from traditional rule-based systems to more flexible, learning-based automation.
He offered specific examples, including a labor optimization agent designed to monitor warehouse workflows and adjust assignments dynamically. These agents are already in production, contributing to operational task management and responding to thousands of user queries.
To support broader adoption, Siotia announced the launch of Agent Foundry—a toolkit for customers to create and deploy their own AI agents. He also noted a strategic collaboration with Google to support interoperability between Manhattan’s AI agents and external platforms, ensuring customers can extend capabilities as needed.
Customer Case Study: Duluth Trading Company
AJ Sutera, Senior Vice President, Chief Technology & Logistics, of Duluth Trading Company, presented a customer case study highlighting the retailer’s digital transformation over the past several years. He outlined the company’s approach to rethinking fulfillment, digital strategy, and channel operations, particularly as part of a major warehouse automation investment.
Sutera described a $60 million project to build an automated fulfillment center in Adairsville, Georgia, launched in September 2023. The initiative was supported by partners including Manhattan Associates, Summit Advisory Services, and others. According to Sutera, the facility has improved operational metrics related to order accuracy, fulfillment speed, and labor efficiency.
His remarks focused on change management as much as technology—emphasizing the need for new skills, clearer roles, and accountability across teams during the transformation process. He credited strong partnerships and coordinated execution as key factors in the project’s success.
Ann Ruckstuhl: Platform Availability and Ecosystem Partnerships
Ann Ruckstuhl, Senior Vice President & CMO
Ann Ruckstuhl, Senior Vice President & CMO, concluded the session by discussing Manhattan’s go-to-market ecosystem. She confirmed that Manhattan Active Solutions are now listed on the Google Cloud Marketplace, increasing availability and simplifying access for enterprise buyers.
Ruckstuhl discussed the company’s partner strategy, including collaboration with Shopify and Google to expand AI-enabled solution delivery. These partnerships are intended to support more flexible deployment options and help customers build integrated commerce experiences.
She encouraged attendees to explore current capabilities through the Unity Pavilion and hands-on demonstrations, which included AI agent use cases, platform configurability, and roundtable discussions on sector-specific applications.
Manhattan Associates used the keynote to communicate its continued investment in unified system design, AI functionality, and customer enablement. The leadership transition from Eddie Capel to Eric Clark was framed as a handoff aligned with the company’s existing direction.
With live deployments of unified applications, practical AI agents in use, and new tools for customer-led development, the company is positioning itself for scalable execution across complex supply chain environments. The focus remains on reducing system fragmentation, simplifying operations, and improving business responsiveness in a dynamic global market.
The post Manhattan Associates’ Strategic Vision – Unifying Platforms Integrating AI and Leading the Future appeared first on Logistics Viewpoints.
You may like
Non classé
Walmart’s $6 Billion Automation Bet and DHL’s Orchestration Strategy: Two Playbooks, One Hard Question
Published
3 jours agoon
13 novembre 2026By
Two announcements in the past three weeks sum up where warehouse automation stands at the end of 2026. On October 29, Walmart and Symbotic expanded their commercial agreement to bring more automation to 25 U.S. regional distribution centers, with an initial commitment of roughly $6 billion spread over several years. Eleven days later, DHL Supply Chain described a very different path: it is scaling the robots it already runs, moving AI orchestration into live warehouses, and piloting what it calls adaptive robotics.
Both are spending heavily, but betting on different ideas about what makes automation pay. For most operators, who are neither Walmart nor DHL, the difference between those ideas matters more than the size of either announcement.
Playbook One: One Vendor, One System, Network Scale
Walmart’s approach is consolidation. Symbotic now supplies a full system rather than a single product: high-density case storage, BreakPack for picking individual items, and SymMicro for store-based e-commerce fulfillment, all run by Symbotic’s own software. Walmart says the expansion will support e-commerce inventory upstream, add storage capacity and make replenishment more reliable.
When one company owns the storage structure, the robots and the control software, there are fewer handoffs between systems from different vendors, and fewer places for goods to pile up when one system cannot see what another is doing. The track record also lends weight. Symbotic reported fiscal third-quarter revenue of $721 million, up 22% year over year, with 56 systems operating and 77 in deployment. Symbotic reported in August that deployment of BreakPack had begun at half of Walmart’s regional distribution centers.
Still, this is a commitment, not a result, and key pieces are still being proven. The first next-generation SymMicro unit was expected to take about six months to install at a Walmart store, and a possible order for 400 back-of-store systems depends on validating that second version. Symbotic itself has said its next revenue and margin inflection is expected in the second half of fiscal 2027.
Playbook Two: Many Robots, One Brain
DHL Supply Chain is betting on coordination rather than consolidation. The company says it has deployed more than 9,000 robots, completed more than 1.5 billion robotic picks and unloaded more than 10 million cases using Boston Dynamics’ Stretch robot. More than 95% of its global warehouses already use advanced digital tools.
The next step is orchestration. After a proof of concept, DHL is putting AI orchestration into live operations as a digital control layer that links data, workers and automated equipment. One workflow it is testing connects mobile robots, packaging automation and the warehouse management system so that resources shift with real-time order demand.
That approach suits a contract logistics provider. DHL serves many customers in many buildings, often on shorter contracts than a retailer would accept for a fixed system. Flexibility is the business model. DHL frames the goal as adding to its workforce, not replacing it. These investments support DHL Group’s broader Strategy 2030 ambition of increasing revenue by 50%.
The Reality Check Most Headlines Skip
Adoption across the market is still thin. Link Logistics, citing Kardex data, reports that about 63% of North American warehouse operations remain fully manual and only about 6% are highly automated, a share that has barely changed since 2024. Integration commonly takes 12 to 18 months and can run past two years for larger systems.
GXO offers another useful reality check. The company is expanding its partnership with Agility Robotics, with Digit humanoids scheduled for deployment at two additional U.S. facilities in 2027. Yet in August, CEO Patrick Kelleher acknowledged that humanoids had not achieved satisfactory returns on investment and that scaled production remained some years away. GXO expects approximately 20,000 robots across its network by year-end, illustrating the considerable distance between conventional robotics adoption and humanoid commercialization.
Scale is still the deciding factor. Walmart can justify a dedicated, end-to-end system because its volume is so large. DHL can justify an orchestration layer because it spreads that investment across more than 9,000 robots and a global network of warehouses.
What Operators Should Ask Before Choosing a Path
For mid-sized shippers, distributors and 3PLs, the lesson is not to copy either company but to be clear about the problem being solved. Four questions help:
Is volume stable enough to justify fixed automation? Dense, integrated systems reward predictable, high-volume flow. Volatile demand favors mobile robots that can be redeployed.
Who owns the control software? Mixing equipment from different suppliers without a single coordinating layer can create bottlenecks at every handoff. Decide who directs the work before buying the hardware.
What happens after go-live? Ask suppliers for evidence on uptime, maintenance cost, recovery from faults and throughput in month 18, not just at commissioning.
Where do people fit? Both Walmart and DHL describe automation as simplifying work for employees rather than removing them. Training, exception handling and clear decision rules for when a robot hands off to a person belong in the business case.
The Bottom Line
Walmart’s $6 billion commitment shows what a single, tightly integrated system can look like at network scale. DHL’s update shows how orchestration can turn a large, mixed robot fleet into one operation. For everyone else, the more useful question is which approach matches their own volume, contracts and tolerance for risk.
The post Walmart’s $6 Billion Automation Bet and DHL’s Orchestration Strategy: Two Playbooks, One Hard Question appeared first on Logistics Viewpoints.
Non classé
Walmart’s $6 Billion Automation Bet and DHL’s Orchestration Strategy: Two Playbooks, One Hard Question
Published
3 jours agoon
13 novembre 2026By
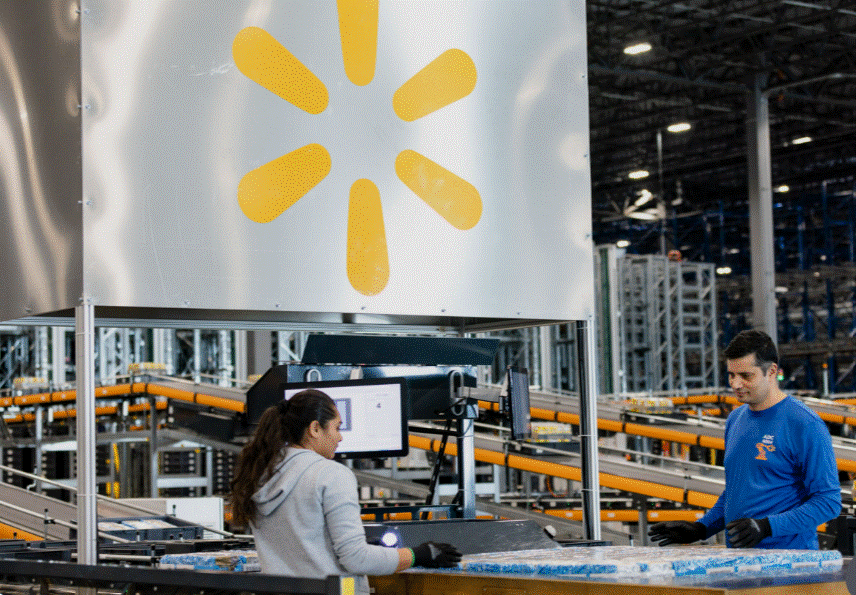
Two announcements in the past three weeks sum up where warehouse automation stands at the end of 2026. On October 29, Walmart and Symbotic expanded their commercial agreement to bring more automation to 25 U.S. regional distribution centers, with an initial commitment of roughly $6 billion spread over several years. Eleven days later, DHL Supply Chain described a very different path: it is scaling the robots it already runs, moving AI orchestration into live warehouses, and piloting what it calls adaptive robotics.
Both are spending heavily, but betting on different ideas about what makes automation pay. For most operators, who are neither Walmart nor DHL, the difference between those ideas matters more than the size of either announcement.
Playbook One: One Vendor, One System, Network Scale
Walmart’s approach is consolidation. Symbotic now supplies a full system rather than a single product: high-density case storage, BreakPack for picking individual items, and SymMicro for store-based e-commerce fulfillment, all run by Symbotic’s own software. Walmart says the expansion will support e-commerce inventory upstream, add storage capacity and make replenishment more reliable.
When one company owns the storage structure, the robots and the control software, there are fewer handoffs between systems from different vendors, and fewer places for goods to pile up when one system cannot see what another is doing. The track record also lends weight. Symbotic reported fiscal third-quarter revenue of $721 million, up 22% year over year, with 56 systems operating and 77 in deployment. Symbotic reported in August that deployment of BreakPack had begun at half of Walmart’s regional distribution centers.
Still, this is a commitment, not a result, and key pieces are still being proven. The first next-generation SymMicro unit was expected to take about six months to install at a Walmart store, and a possible order for 400 back-of-store systems depends on validating that second version. Symbotic itself has said its next revenue and margin inflection is expected in the second half of fiscal 2027.
Playbook Two: Many Robots, One Brain
DHL Supply Chain is betting on coordination rather than consolidation. The company says it has deployed more than 9,000 robots, completed more than 1.5 billion robotic picks and unloaded more than 10 million cases using Boston Dynamics’ Stretch robot. More than 95% of its global warehouses already use advanced digital tools.
The next step is orchestration. After a proof of concept, DHL is putting AI orchestration into live operations as a digital control layer that links data, workers and automated equipment. One workflow it is testing connects mobile robots, packaging automation and the warehouse management system so that resources shift with real-time order demand.
That approach suits a contract logistics provider. DHL serves many customers in many buildings, often on shorter contracts than a retailer would accept for a fixed system. Flexibility is the business model. DHL frames the goal as adding to its workforce, not replacing it. These investments support DHL Group’s broader Strategy 2030 ambition of increasing revenue by 50%.
The Reality Check Most Headlines Skip
Adoption across the market is still thin. Link Logistics, citing Kardex data, reports that about 63% of North American warehouse operations remain fully manual and only about 6% are highly automated, a share that has barely changed since 2024. Integration commonly takes 12 to 18 months and can run past two years for larger systems.
GXO offers another useful reality check. The company is expanding its partnership with Agility Robotics, with Digit humanoids scheduled for deployment at two additional U.S. facilities in 2027. Yet in August, CEO Patrick Kelleher acknowledged that humanoids had not achieved satisfactory returns on investment and that scaled production remained some years away. GXO expects approximately 20,000 robots across its network by year-end, illustrating the considerable distance between conventional robotics adoption and humanoid commercialization.
Scale is still the deciding factor. Walmart can justify a dedicated, end-to-end system because its volume is so large. DHL can justify an orchestration layer because it spreads that investment across more than 9,000 robots and a global network of warehouses.
What Operators Should Ask Before Choosing a Path
For mid-sized shippers, distributors and 3PLs, the lesson is not to copy either company but to be clear about the problem being solved. Four questions help:
Is volume stable enough to justify fixed automation? Dense, integrated systems reward predictable, high-volume flow. Volatile demand favors mobile robots that can be redeployed.
Who owns the control software? Mixing equipment from different suppliers without a single coordinating layer can create bottlenecks at every handoff. Decide who directs the work before buying the hardware.
What happens after go-live? Ask suppliers for evidence on uptime, maintenance cost, recovery from faults and throughput in month 18, not just at commissioning.
Where do people fit? Both Walmart and DHL describe automation as simplifying work for employees rather than removing them. Training, exception handling and clear decision rules for when a robot hands off to a person belong in the business case.
The Bottom Line
Walmart’s $6 billion commitment shows what a single, tightly integrated system can look like at network scale. DHL’s update shows how orchestration can turn a large, mixed robot fleet into one operation. For everyone else, the more useful question is which approach matches their own volume, contracts and tolerance for risk.
The post Walmart’s $6 Billion Automation Bet and DHL’s Orchestration Strategy: Two Playbooks, One Hard Question appeared first on Logistics Viewpoints.
Non classé
The Next Logistics Capacity Investment May Not Be Another Building
Published
3 jours agoon
13 novembre 2026By
When a distribution center begins to run out of capacity, the conversation usually turns to physical expansion. The company may need another building, a larger yard, additional dock doors, more equipment, or a second site closer to customers. Those are familiar decisions, supported by familiar metrics: square footage, pallet positions, average volume, and the cost of carrying another lease.
There is a question that should come before the capital request. Is the network actually short of physical capacity, or is too much of the capacity it already owns being lost between activities? A dock door waiting for a late trailer is technically available but not productive. A switcher that cannot identify the next trailer to move is on the payroll but not adding throughput. A shipment that cannot be scheduled may tie up inventory even while the warehouse has labor ready to load it.
The answer matters because building capacity and recovering capacity are different investments. One expands the physical system; the other improves how the existing system is used. In the right circumstances, the second can deliver faster returns with less capital at risk. It will not eliminate every expansion, but it can prevent companies from mistaking operational friction for a structural shortage.
Red Gold illustrates the capacity hidden in scheduling
Food manufacturer Red Gold offers a concrete example. Its distribution operations once depended on large volumes of phone calls and email exchanges to coordinate dock appointments. In peak periods, some carriers could face a wait of two weeks to book a slot. That scheduling delay did not mean the operation had no physical space in an absolute sense; it meant access to available capacity was poorly coordinated.
In a case study published by Opendock and Loadsmart, Red Gold reported moving more than 60,000 annual appointments into online carrier self-scheduling. Appointment lead times fell 90%, from double-digit days to roughly one or two days, and case throughput increased 18%. The customer also introduced transportation management and brokerage changes, including ShipperGuide. It would therefore be too simplistic to credit every improvement to a single scheduling product.
The operational logic is nevertheless compelling. Advance notice allows a facility to stage orders, allocate docks and labor, and reduce the uncertainty created by a constant stream of last-minute phone calls. Employees who previously entered appointments can devote more attention to exceptions. Carriers gain a clearer path to an available slot instead of repeatedly contacting the shipper to discover one.
None of that creates new square footage. It improves the utilization of the square footage already present, which is exactly why scheduling belongs in a capital planning conversation rather than being classified as an administrative convenience.
Rated capacity is not realized capacity
Capacity planning often treats the warehouse as a set of tangible resources: doors, lift trucks, people, storage positions, conveyor rates, or pick locations. But the actual output of those resources depends on synchronization. A dock cannot be productive merely because it exists; freight, equipment, documentation, labor, and a usable appointment window must arrive together.
Consider a simplified facility with 30 dock doors operating across sixteen scheduled hours, with each transaction averaging two hours of door time. Its theoretical, uninterrupted maximum is 240 trailer transactions per day. At 70% productive occupancy, that falls to 168. Increasing productive occupancy to 80% yields 192 transactions—a gain of approximately 14% relative to realized throughput. These figures are an illustration, not a real facility result, and they assume receiving, storage, and shipping operations can absorb the extra volume.
That caveat is crucial. No facility should be operated at 100% utilization at all times. Maintenance, arrival variability, worker safety, late orders, and disruption recovery require buffer capacity. The objective is not to eliminate slack indiscriminately. It is to distinguish deliberate resilience from avoidable idle time, and then determine what the extra capacity would actually be worth.
The same argument applies across a multi-site network. One overloaded facility and one underutilized facility do not necessarily offset each other, because the freight may be in the wrong place, on the wrong timetable, or attached to the wrong customer commitments. The right unit of analysis is the flow of orders through the network, not simply aggregate square footage.
What dock coordination can recover
GoBolt offers an example closer to the receiving operation. In a 2025 Opendock customer case study, the fulfillment provider reported a 20% improvement in inbound receiving efficiency after replacing fragmented appointment coordination with a more consistent scheduling process. The company also reported recovering 10 to 15 hours of administrative work each week. Those are provider-published operational results, not an audited calculation of avoided building investment, but they show how better arrival predictability can help a receiving team extract more work from its existing doors and shifts.
The distinction between receiving efficiency and physical expansion is important. If more freight can be accepted and processed in the same labor window, management may have room to defer a capital project or meet a seasonal peak without adding a shift. That conclusion requires evidence: gate-to-door time, unload duration, dock-to-stock performance, staffing, and the utilization of downstream storage and putaway resources. A faster appointment system alone cannot prove that the entire facility has gained equivalent usable capacity.
Ralph Moyle, a food-and-beverage warehousing and transportation provider, presents a second dimension of the problem. Its operation coordinated as many as 500 weekly appointments across 37 dock doors. According to an Opendock case study published in November 2025, the organization reduced labor devoted to dock scheduling by more than 30% and gained clearer information on carrier punctuality and detention windows. This is a scheduling-labor result, not a published 30% improvement in warehouse throughput. It nonetheless illustrates a recurring investment choice: deploy scarce people against routine coordination, or free them to handle the exceptions and operating constraints that determine service.
Together, Red Gold, GoBolt, and Ralph Moyle suggest a capital-planning sequence rather than a universal savings percentage. First, measure whether appointment variability and inefficient handoffs are preventing existing assets from delivering their designed throughput. Next, test a bounded change to scheduling and execution, measuring both operational output and service reliability under actual peak conditions. Only then compare recovery investments against a larger building, additional doors, or other capacity additions. Supplier case studies establish plausible mechanisms; the company’s own operational and financial baseline must establish the return.
Treat avoided capital as an option, not a guaranteed saving
There is a temptation to translate every percentage point of productivity improvement into a claim that a new warehouse can be avoided. That overstates the evidence. A throughput gain at one dock or yard may merely move congestion downstream to picking, storage, staging, or outbound transportation. It may also be insufficient to cover peak demand, seasonal swings, or a required redundancy plan.
A rigorous alternative-to-expansion study should therefore define the specific capacity shortage and test the whole process. Start with actual hourly and daily flow data, not averages alone. Identify the constraining resource under peak conditions. Determine the amount of lost capacity attributable to preventable waiting or information errors, estimate the cost to recover it, and confirm that other resources can absorb the improvement. Compare that option with expansion through a common net-present-value analysis, including implementation risk, service impact, and flexibility.
For the CFO, the value of operational improvement is often optionality. A relatively modest investment in scheduling, yard coordination, or workflow redesign may postpone a lease commitment, provide better evidence about the true need for new space, or help size a future facility more accurately. Deferral is not the same as permanently avoiding an investment, and the distinction should appear in the financial model.
For operations leaders, this changes the questions asked of technology vendors. Instead of buying ‘visibility’ or ‘AI’ as abstract capabilities, they can ask what utilization constraint will be removed, what operating metric should change, who must act on the information, and how quickly a measurable result should appear.
The next warehouse may eventually be necessary. Demand growth, service commitments, and network resilience will continue to require physical expansion. But before pouring concrete, companies should understand how much of their current investment is stranded in queues, mismatched schedules, and preventable handoffs. More capacity sometimes starts with another building. Sometimes it starts with getting tomorrow’s truck into the right dock today.
The post The Next Logistics Capacity Investment May Not Be Another Building appeared first on Logistics Viewpoints.

Walmart’s $6 Billion Automation Bet and DHL’s Orchestration Strategy: Two Playbooks, One Hard Question
Walmart’s $6 Billion Automation Bet and DHL’s Orchestration Strategy: Two Playbooks, One Hard Question
The Next Logistics Capacity Investment May Not Be Another Building
Freightos Global Freight Outlook – September 2026
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update

Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
Trending
- Non classé3 mois ago
Freightos Global Freight Outlook – September 2026
- Non classé4 mois ago
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update
-
 Non classé2 ans ago
Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
-
 Non classé7 mois ago
Why Sulfuric Acid Is Emerging as a Supply Chain Constraint in Copper
- Non classé6 mois ago
Container rates starting to spike on peak season rush – June 2, 2026 Update
- Non classé1 an ago
13 Books Logistics And Supply Chain Experts Need To Read
- Non classé1 an ago
Ex-Asia ocean rates climb on GRIs, despite slowing demand – October 22, 2025 Update
- Non classé4 mois ago
LCL Shipping Cost Calculator: Calculate Air and Sea Shipping Freight Rates