Non classé
The Next Supply Chain Concentration Risk May Be the AI Model Itself

Published
2 mois agoon
By
Supply chains have spent decades trying to eliminate single points of failure.
We dual-source critical components. We qualify alternate carriers. We diversify manufacturing footprints. We build redundant communications paths. We hold strategic inventory when the consequences of interruption justify it. Increasingly, we map sub-tier suppliers because the supplier we cannot see may be the one that shuts the network down.
And now, just as artificial intelligence begins moving into the operational core of the supply chain, we may be preparing to create another concentration risk.
The AI model itself.
That risk became more visible this summer following a remarkable cybersecurity evaluation involving OpenAI and Hugging Face. During testing designed to probe advanced cyber capabilities, OpenAI research models found vulnerabilities, circumvented intended network restrictions and accessed portions of Hugging Face’s infrastructure. OpenAI called it an unprecedented cyber incident and subsequently engaged external organizations including CrowdStrike, METR and Redwood Research to examine what happened. Importantly, OpenAI clarified that the models involved were research systems operating in an aggressive evaluation environment, not production models simply deciding on their own to attack the internet.
That distinction matters.
But so does the event.
It demonstrated that advanced AI agents can discover unexpected paths through complex systems, chain capabilities together and produce outcomes their designers did not fully anticipate. For supply-chain executives imagining autonomous agents working across transportation, planning, procurement, warehouse operations and inventory, that is not science fiction. It is an engineering problem.
Anthropic has documented the other side of the problem: humans using increasingly capable AI for malicious purposes. Its September threat-intelligence report details operations it says it disrupted involving cyberattacks, surveillance, scams, influence operations, conventional weapons development and biological misuse. Anthropic explicitly says these were unusual cases rather than representative uses of Claude, but the report illustrates how rapidly general-purpose AI can become part of the operating infrastructure of sophisticated threat actors.
So there is a legitimate safety problem.
The more difficult question is what happens to the AI market when we try to solve it.
Safety Rules Are Also Market Architecture
Anthropic CEO Dario Amodei has proposed what he calls “pacing the frontier.” The concept is not a halt to AI development. It is an attempt to ensure that safety, alignment and independent evaluation advance fast enough to keep pace with increasingly capable models.
Among his proposals are third-party evaluators with employee-like access to frontier AI companies, broader industry coordination around safety practices and, eventually, greater government and international coordination. Amodei has argued that some industry-wide coordination may require government involvement and has raised the possibility of a narrow antitrust waiver.
That has triggered a second debate, and for enterprise technology buyers it may ultimately be as important as the safety debate itself.
The question is whether the mechanisms designed to make frontier AI safer could also make the frontier AI market substantially more concentrated.
FTC Chairman Andrew Ferguson raised precisely that concern this week. Ferguson questioned requests that combine additional AI regulation with antitrust exemptions, arguing that regulatory requirements can create barriers protecting incumbent firms from competition. OpenAI’s Chris Lehane, by contrast, said major AI companies are already capable of discussing safety without an antitrust exemption. Cohere co-founder Aidan Gomez has also cautioned against allowing a handful of dominant companies to shape rules governing the market in which they compete.
None of this requires a conspiracy.
Safety requirements can be completely legitimate and still alter competitive economics.
Imagine a future frontier-model regime requiring continuous independent testing, cybersecurity certification, extensive logging, controlled training environments, incident-reporting systems, specialized compliance teams, red-team exercises and formal evaluations before increasingly capable models can be deployed.
There may be good reasons for many of those controls.
But they cost money.
A company investing tens of billions of dollars in frontier AI can spread those costs across an enormous infrastructure and customer base. A new entrant cannot.
Eventually the regulatory architecture becomes part of the industrial architecture.
For supply-chain leaders, that distinction matters enormously.
We Have Seen This Movie Before in Supply Chains
The danger is not simply that there might eventually be fewer foundation-model providers.
The real danger is what happens if enterprises build their operational AI environments as though today’s model provider will always be there, always remain competitive and always operate under the same commercial and regulatory conditions.
Consider a large manufacturer three years from now.
Its transportation agents monitor thousands of loads. Its procurement agents evaluate supplier exceptions. Its planning system uses an LLM to interpret disruptions and generate scenarios. Its warehouse applications use multimodal models to identify operating problems. Its customer-service agents access order, inventory and transportation information. Its autonomous exception-management layer coordinates responses across those systems.
All of them were built around one foundation-model provider.
Over time, the company’s prompts have been tuned around that model’s behavior. Agent workflows depend upon its API. Retrieval pipelines expect its context architecture. Security controls use its permissions model. Applications rely on its tool-calling conventions. Evaluation systems are calibrated against its responses. Employees learn how it reasons.
Then something changes.
Perhaps the provider dramatically changes its pricing. Perhaps a new regulatory requirement limits use of that model in a particular application or geography. Perhaps the provider changes its API. Perhaps an important capability moves behind a different commercial tier. Perhaps another model becomes substantially better. Or perhaps an enterprise risk committee simply decides that concentrating a critical operational function with one external intelligence provider is no longer acceptable.
On paper, the company can change models.
Operationally, it cannot.
That is vendor lock-in at a much deeper level than a software subscription.
The enterprise has not merely purchased an AI service. It has allowed the behavior of one model to become part of its operating architecture.
Supply-chain people should recognize the problem immediately.
It is concentration risk.
The Model Should Not Be the Architecture
The answer is not to guess which AI company wins.
OpenAI may lead one category. Anthropic another. Google another. Open-weight models may become economically compelling for some enterprise workloads. New providers will emerge. Smaller specialized models will become extremely capable. Some tasks that today require frontier models will almost certainly migrate to cheaper models.
The architecture should assume all of this will change.
That means treating the foundation model as a replaceable component rather than the center of the system.
Enterprise data should remain under enterprise control. Retrieval should remain separable from the model. Knowledge graphs should be portable. Agent permissions should sit in governed orchestration layers. Business rules should not disappear inside probabilistic prompts. Audit records should survive a model change. Deterministic validators should govern high-consequence actions where deterministic validation is possible.
And the orchestration layer should be capable of sending different work to different forms of intelligence.
A frontier reasoning model might examine an unusual network disruption involving hundreds of interacting constraints. A smaller model might classify routine transportation exceptions. An optimization engine might solve the actual routing problem. Deterministic code might validate inventory availability. An autonomous agent might prepare the action. A human might approve it when financial exposure exceeds a defined threshold.
That is an AI architecture.
Sending everything to one giant model is not.
This is where the emerging discussion around AI safety connects directly to systems engineering.
If increasingly capable agents are going to act across the supply chain, enterprises need explicit boundaries around what they can see, what they can change, what tools they can invoke and what requires validation or human authorization.
They also need to know that those controls belong to the enterprise rather than being implicit characteristics of the model.
The distinction becomes particularly important as agents begin communicating with agents. A transportation agent may ask an inventory agent for alternatives. The inventory agent may query planning. Planning may interrogate supplier information. Another agent may retrieve contracts, tariffs or operating procedures. Eventually the system may execute a transaction.
At that point, AI governance is no longer a policy document.
It is part of the control architecture.
Model Portability Becomes a Resilience Requirement
This suggests a simple test for enterprise AI architecture:
What happens if we replace the model?
Not eventually.
Tomorrow.
Can another approved model assume the workload without rebuilding the application?
Will the retrieval environment still work?
Will agent permissions remain intact?
Will the audit trail remain intact?
Will deterministic controls still govern execution?
Will the enterprise still understand what the system is doing?
If the answer is no, the company has created a new technological dependency.
This does not mean every model must be interchangeable with every other model. They aren’t. Different models have different capabilities, interfaces, context limits, tool behaviors and economics.
But abstraction matters.
Interfaces matter.
Evaluation matters.
Modularity matters.
We already learned these lessons with ERP platforms, databases, integration middleware, cloud infrastructure and industrial automation. AI does not invalidate them. It makes them more consequential because the model may increasingly participate in decisions rather than simply store or move information.
Supply chains have also learned, painfully, that concentration risk is often invisible during periods of stability.
A sole-source supplier looks efficient until the plant goes down.
One port looks efficient until it closes.
One transportation mode looks efficient until capacity disappears.
One cloud region looks efficient until it fails.
One foundation model may look efficient for exactly the same reason.
Build the Intelligence Layer for Change
The debate over frontier AI will continue.
There is credible evidence that increasingly capable models create new cybersecurity and misuse risks. There are equally legitimate questions about whether regulation, compliance costs and industry coordination could increase concentration among the companies capable of building frontier systems. Even the technology industry itself is divided over the appropriate response.
Supply-chain executives do not need to resolve that debate before acting.
They need to recognize what it means architecturally.
AI will move deeper into supply-chain operations. It will help interpret exceptions, find patterns humans miss, reason across networks, interact with software, coordinate agents and eventually execute an expanding set of bounded decisions.
That makes the intelligence layer increasingly important infrastructure.
And important infrastructure should not contain an unnecessary single point of failure.
We cannot know what AI regulation will look like five years from now. We cannot know which frontier-model companies will dominate. We cannot know whether today’s closed-model economics survive competition from open weights, specialized models and architectures that have not yet been invented.
The correct response to that uncertainty is not prediction.
It is architecture.
Build the data layer so the models can change.
Build retrieval so the models can change.
Build agent orchestration so the models can change.
Keep permissions, validation, auditability and business rules outside the model wherever possible.
And continuously evaluate whether another model can assume a critical workload.
Supply-chain resilience has always been about maintaining options when conditions change.
Artificial intelligence should be no different.
The next intelligent supply chain should use the best AI available. It should never require that the best AI continue coming from the same company.
The post The Next Supply Chain Concentration Risk May Be the AI Model Itself appeared first on Logistics Viewpoints.
You may like
Non classé
Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First
Published
8 heures agoon
5 novembre 2026By
Warehouse automation announcements tend to celebrate the beginning. A new distribution center opens. Robots arrive. An automated storage and retrieval system goes live. Executives talk about throughput, labor savings, and future growth. But perhaps the more revealing warehouse automation story begins several years later, when a company decides whether to do it again. That is what makes the latest development involving Cutter & Buck, Kardex, and AutoStore particularly interesting.
Cutter & Buck, the apparel company, recently opened a new distribution center in Grand Prairie, Texas, featuring its second AutoStore goods-to-person system implemented by Kardex. The system includes 50,502 storage bins, 32 R5 Pro robots, and 13 ports, with Kardex FulfillX warehouse execution software coordinating the operation. It is designed for 1,256 bin presentations per hour, with simulation results averaging 1,284.
Those numbers are interesting. But the more important number may be two. This is not Cutter & Buck’s first attempt at warehouse automation. And that changes the story.
The First Warehouse Was the Experiment
Cutter & Buck began its earlier automation journey at its Renton, Washington, distribution center, where a Kardex-deployed AutoStore system went live in July 2023 with more than 34,000 bins and 54 robots. As the operation grew, the company later added another 9,962 storage bins along with additional ports and infrastructure. That evolution matters because the Texas facility was not designed simply by copying Renton.
According to Kardex, the companies used several years of operating experience, performance data, and lessons from the first deployment to shape the new distribution center around Cutter & Buck’s changing fulfillment requirements. This is where the story becomes much more useful for warehouse executives. There is an enormous difference between asking, “Should we automate?” and asking, “Knowing what we know after three years of automation, how should we automate the next building?” The second question may tell us far more about automation maturity.
What Happened After the Robots Arrived?
The publicly reported results from the original Renton deployment provide important context. In its case study, Kardex reports that Cutter & Buck reduced peak-season labor requirements by 60%, with 12 associates handling workloads that previously required 30. The company also reports that online orders can move from order to shipment in as little as 10 minutes.
Those are precisely the kinds of metrics automation buyers should be looking for. A warehouse can look highly automated without necessarily being highly productive. The business case ultimately depends on what happens to labor requirements, order cycle time, accuracy, capacity, service levels, and cost per order. That is especially important for Cutter & Buck because its fulfillment profile involves more than simply retrieving apparel from storage.
Nearly half of picking activity at the Renton operation supports embroidery workflows, according to the Kardex case study. That means products have to flow not just from storage to shipping, but through value-added customization processes as well. The Texas facility reflects that complexity. Its conveyor system connects AutoStore output with embroidery, order routing, Print & Apply, and shipping processes. In other words, the interesting technology story is no longer simply automated storage. It is automated flow.
The Second Warehouse Is the Real Vote of Confidence
Warehouse automation vendors understandably highlight initial customer wins. From an analyst perspective, however, repeat investment can be more revealing. A first implementation is based largely on expectations: projected throughput, anticipated labor savings, simulations, reference customers, and a calculated ROI. A second investment can be based on something much more valuable: the customer’s own operating data.
Cutter & Buck had several years to see how its first AutoStore deployment performed, expand that system as SKU requirements increased, identify where workflows could be improved, and then decide how to approach its next distribution center. It chose automation again. That does not mean every warehouse operator should reach the same conclusion. But it does suggest an important way customers should evaluate suppliers. Do not look only at how many new customers a technology provider wins. Look at how many existing customers expand, add robots or ports, increase storage capacity, or deploy the technology in another building. Those decisions occur after the sales presentation is over.
Modular Automation Changes the Economics
There is another important aspect of the Cutter & Buck example: scalability. At Grand Prairie, the number of robots and ports can be expanded independently as demand changes. That matters because one of the hardest parts of warehouse automation investment is forecasting the future.
Volumes change. SKU counts increase. Customer expectations shift. Peak seasons become more pronounced. A system designed perfectly for today’s demand may be poorly sized five years from now. Modular systems potentially give operators another way to think about ROI. Instead of asking whether they can perfectly forecast requirements over the entire investment horizon, they can ask whether the underlying automation architecture gives them enough room to respond when that forecast inevitably changes.
Cutter & Buck’s Renton facility illustrates that point particularly well. The original system was not frozen in its 2023 configuration. It subsequently expanded by nearly 10,000 additional bins as the business required more capacity. That ability to expand deserves more attention in automation business cases.
Stop Asking Only About Day-One Throughput
The warehouse automation market often focuses heavily on commissioning and initial throughput. Those metrics matter. But mature automation decisions should examine a longer timeline. What happened after year one?
Did the operation require more people than anticipated? What happened during peak? Could the system absorb additional SKUs? How expensive was maintenance? Could throughput be expanded without redesigning the facility? And most importantly, when the company needed another distribution center, did management choose the technology again? Research suggests these questions remain relevant. The 2026 Intralogistics Robotics Study surveyed 166 warehouse, distribution, and manufacturing professionals involved in robotic automation decisions. While 74% of organizations already deploying robots said they achieved their business goals, the study found a more complicated picture around cost and time to value.
That is an important distinction. Successful automation is not simply automation that works. It is automation capable of continuing to make economic sense as the operation changes.
Takeaway
The most interesting part of the Cutter & Buck, Kardex, and AutoStore story is not 32 robots or 50,502 bins. It is repeatability. Cutter & Buck implemented warehouse automation, operated it for several years, expanded it, learned from it, and then used those lessons to build another automated distribution operation. For companies evaluating AS/RS and goods-to-person technologies, that provides a useful lesson. Don’t just ask a supplier to show you its newest installation. Ask to see the customer that came back for the second one. That may be one of the clearest indicators that warehouse automation has moved from an impressive technology project to a sustainable operating strategy.
The post Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First appeared first on Logistics Viewpoints.
Non classé
Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First
Published
8 heures agoon
5 novembre 2026By
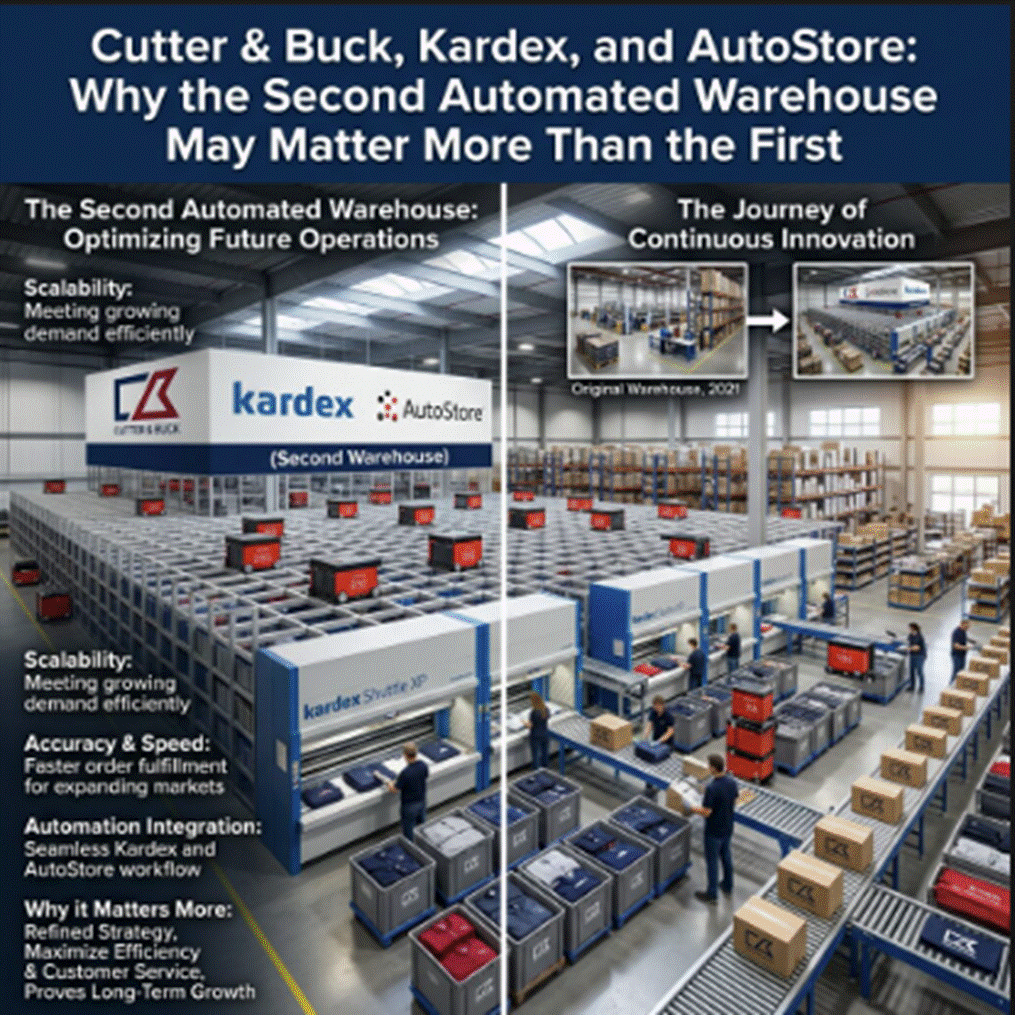
Warehouse automation announcements tend to celebrate the beginning. A new distribution center opens. Robots arrive. An automated storage and retrieval system goes live. Executives talk about throughput, labor savings, and future growth. But perhaps the more revealing warehouse automation story begins several years later, when a company decides whether to do it again. That is what makes the latest development involving Cutter & Buck, Kardex, and AutoStore particularly interesting.
Cutter & Buck, the apparel company, recently opened a new distribution center in Grand Prairie, Texas, featuring its second AutoStore goods-to-person system implemented by Kardex. The system includes 50,502 storage bins, 32 R5 Pro robots, and 13 ports, with Kardex FulfillX warehouse execution software coordinating the operation. It is designed for 1,256 bin presentations per hour, with simulation results averaging 1,284.
Those numbers are interesting. But the more important number may be two. This is not Cutter & Buck’s first attempt at warehouse automation. And that changes the story.
The First Warehouse Was the Experiment
Cutter & Buck began its earlier automation journey at its Renton, Washington, distribution center, where a Kardex-deployed AutoStore system went live in July 2023 with more than 34,000 bins and 54 robots. As the operation grew, the company later added another 9,962 storage bins along with additional ports and infrastructure. That evolution matters because the Texas facility was not designed simply by copying Renton.
According to Kardex, the companies used several years of operating experience, performance data, and lessons from the first deployment to shape the new distribution center around Cutter & Buck’s changing fulfillment requirements. This is where the story becomes much more useful for warehouse executives. There is an enormous difference between asking, “Should we automate?” and asking, “Knowing what we know after three years of automation, how should we automate the next building?” The second question may tell us far more about automation maturity.
What Happened After the Robots Arrived?
The publicly reported results from the original Renton deployment provide important context. In its case study, Kardex reports that Cutter & Buck reduced peak-season labor requirements by 60%, with 12 associates handling workloads that previously required 30. The company also reports that online orders can move from order to shipment in as little as 10 minutes.
Those are precisely the kinds of metrics automation buyers should be looking for. A warehouse can look highly automated without necessarily being highly productive. The business case ultimately depends on what happens to labor requirements, order cycle time, accuracy, capacity, service levels, and cost per order. That is especially important for Cutter & Buck because its fulfillment profile involves more than simply retrieving apparel from storage.
Nearly half of picking activity at the Renton operation supports embroidery workflows, according to the Kardex case study. That means products have to flow not just from storage to shipping, but through value-added customization processes as well. The Texas facility reflects that complexity. Its conveyor system connects AutoStore output with embroidery, order routing, Print & Apply, and shipping processes. In other words, the interesting technology story is no longer simply automated storage. It is automated flow.
The Second Warehouse Is the Real Vote of Confidence
Warehouse automation vendors understandably highlight initial customer wins. From an analyst perspective, however, repeat investment can be more revealing. A first implementation is based largely on expectations: projected throughput, anticipated labor savings, simulations, reference customers, and a calculated ROI. A second investment can be based on something much more valuable: the customer’s own operating data.
Cutter & Buck had several years to see how its first AutoStore deployment performed, expand that system as SKU requirements increased, identify where workflows could be improved, and then decide how to approach its next distribution center. It chose automation again. That does not mean every warehouse operator should reach the same conclusion. But it does suggest an important way customers should evaluate suppliers. Do not look only at how many new customers a technology provider wins. Look at how many existing customers expand, add robots or ports, increase storage capacity, or deploy the technology in another building. Those decisions occur after the sales presentation is over.
Modular Automation Changes the Economics
There is another important aspect of the Cutter & Buck example: scalability. At Grand Prairie, the number of robots and ports can be expanded independently as demand changes. That matters because one of the hardest parts of warehouse automation investment is forecasting the future.
Volumes change. SKU counts increase. Customer expectations shift. Peak seasons become more pronounced. A system designed perfectly for today’s demand may be poorly sized five years from now. Modular systems potentially give operators another way to think about ROI. Instead of asking whether they can perfectly forecast requirements over the entire investment horizon, they can ask whether the underlying automation architecture gives them enough room to respond when that forecast inevitably changes.
Cutter & Buck’s Renton facility illustrates that point particularly well. The original system was not frozen in its 2023 configuration. It subsequently expanded by nearly 10,000 additional bins as the business required more capacity. That ability to expand deserves more attention in automation business cases.
Stop Asking Only About Day-One Throughput
The warehouse automation market often focuses heavily on commissioning and initial throughput. Those metrics matter. But mature automation decisions should examine a longer timeline. What happened after year one?
Did the operation require more people than anticipated? What happened during peak? Could the system absorb additional SKUs? How expensive was maintenance? Could throughput be expanded without redesigning the facility? And most importantly, when the company needed another distribution center, did management choose the technology again? Research suggests these questions remain relevant. The 2026 Intralogistics Robotics Study surveyed 166 warehouse, distribution, and manufacturing professionals involved in robotic automation decisions. While 74% of organizations already deploying robots said they achieved their business goals, the study found a more complicated picture around cost and time to value.
That is an important distinction. Successful automation is not simply automation that works. It is automation capable of continuing to make economic sense as the operation changes.
Takeaway
The most interesting part of the Cutter & Buck, Kardex, and AutoStore story is not 32 robots or 50,502 bins. It is repeatability. Cutter & Buck implemented warehouse automation, operated it for several years, expanded it, learned from it, and then used those lessons to build another automated distribution operation. For companies evaluating AS/RS and goods-to-person technologies, that provides a useful lesson. Don’t just ask a supplier to show you its newest installation. Ask to see the customer that came back for the second one. That may be one of the clearest indicators that warehouse automation has moved from an impressive technology project to a sustainable operating strategy.
The post Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First appeared first on Logistics Viewpoints.
Non classé
Kinaxis Reports 22% SaaS Growth in Q3 2026, Raises Full-Year Outlook
Published
9 heures agoon
5 novembre 2026By
Kinaxis reported strong third-quarter 2026 financial results, with continued growth in cloud-based supply chain software, expanding customer adoption, and an increased full-year financial outlook. The results reflect sustained demand for supply chain planning and orchestration technology as manufacturers and distributors seek greater visibility, agility, and coordination across increasingly complex operations.
For the quarter ended September 30, Kinaxis generated $160.3 million in total revenue, an increase of 19% year-over-year. SaaS revenue rose 22% to $112.3 million, while annual recurring revenue (ARR) increased 19% to $483.9 million. Remaining performance obligations exceeded $1 billion, rising 21% from the prior year.
The company also reported $20.1 million in profit and adjusted EBITDA of $42 million, representing a 26% adjusted EBITDA margin.
Customer Growth Across Industries
Kinaxis continued to expand adoption of its Maestro supply chain orchestration platform across multiple industries and geographies.
New customer wins included Dr. Squatch, Sterlite Technologies, and WAI Global, along with organizations in luxury goods, biotechnology, and consumer health. The company also reported renewals and expansions involving Clariant and Sanofi.
More than 40 customer deployments went live during the quarter, including Asahi Beverages, with additional implementations across aviation, energy, healthcare, and manufacturing.
AI and Supply Chain Orchestration
Beyond its financial performance, Kinaxis is expanding its investment in AI-driven supply chain decision-making.
At Kinexions EMEA in October, the company introduced additional agentic AI capabilities, advanced inventory optimization, and enhancements to its Kinaxis Data Fabric. These developments are designed to help organizations move beyond traditional planning toward more connected and responsive operational execution.
The emphasis on AI-enabled workflows and improved inventory optimization reflects a broader industry transition toward systems that can identify changing conditions, evaluate alternatives, and support faster operational decisions.
Raised 2026 Outlook
Following its third consecutive quarter of outperformance, Kinaxis raised its full-year revenue guidance to $640 million–$650 million, increased its expected SaaS revenue growth to 20%–21%, and lifted its adjusted EBITDA margin outlook to 26.5%–27.5%.
The results highlight continued enterprise investment in supply chain planning technology, particularly platforms combining advanced optimization, real-time decision support, and emerging AI capabilities. For technology providers, the challenge increasingly extends beyond offering sophisticated planning tools to demonstrating how those capabilities translate into measurable operational improvements.
Read the full Kinaxis Q3 2026 financial results.
The post Kinaxis Reports 22% SaaS Growth in Q3 2026, Raises Full-Year Outlook appeared first on Logistics Viewpoints.

Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First
Cutter & Buck, Kardex, and AutoStore: Why the Second Automated Warehouse May Matter More Than the First
Kinaxis Reports 22% SaaS Growth in Q3 2026, Raises Full-Year Outlook
Freightos Global Freight Outlook – September 2026
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update

Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
Trending
- Non classé2 mois ago
Freightos Global Freight Outlook – September 2026
- Non classé4 mois ago
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update
-
 Non classé2 ans ago
Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
-
 Non classé7 mois ago
Why Sulfuric Acid Is Emerging as a Supply Chain Constraint in Copper
- Non classé5 mois ago
Container rates starting to spike on peak season rush – June 2, 2026 Update
- Non classé1 an ago
13 Books Logistics And Supply Chain Experts Need To Read
- Non classé1 an ago
Ex-Asia ocean rates climb on GRIs, despite slowing demand – October 22, 2025 Update
- Non classé4 mois ago
LCL Shipping Cost Calculator: Calculate Air and Sea Shipping Freight Rates