Non classé
US Supreme Court Narrows Emergency Tariff Authority: Strategic Implications for Supply Chain Leaders

Published
9 mois agoon
By
In a 6–3 decision, the U.S. Supreme Court ruled that President Trump exceeded his authority by using the International Emergency Economic Powers Act (IEEPA) to impose sweeping global tariffs.
Chief Justice John Roberts, writing for the majority, held that the Constitution assigns tariff authority to Congress and that IEEPA does not clearly authorize the president to impose broad import duties. The ruling invalidates the legal foundation for the administration’s emergency-based “Liberation Day” tariffs and significantly limits the use of IEEPA as a mechanism for imposing duties.
For supply chain leaders, the decision reshapes the structure of tariff risk. It does not eliminate it.
From Emergency Leverage to Statutory Process
Under the IEEPA framework, tariffs were justified through national emergency declarations. The Court rejected the argument that the statute’s authority to “regulate … importation” includes the power to impose tariffs.
What remains are established statutory pathways:
Section 232 national security tariffs
Section 301 actions addressing unfair trade practices
Section 201 safeguards responding to import surges
Temporary authorities under the Trade Act
Each requires investigation, defined scope, and procedural steps. This changes how tariff actions are initiated and implemented. It does not remove executive trade leverage.
Strategic Implications
Tariff Risk Becomes More Structured
The likelihood of broad, open-ended tariffs imposed solely under emergency authority is now reduced.
Future tariff actions are more likely to:
Target specific industries or countries
Follow investigation timelines
Include defined duration parameters
For supply chain leaders, this means greater visibility into potential actions before they take effect. Monitoring investigation announcements and regulatory developments becomes essential.
Industry Exposure Becomes a Core Variable
If tariff actions shift toward sector-specific measures, industry classification matters as much as geography.
Leaders should ensure visibility into:
Product classification under trade statutes
Exposure to industries historically subject to Section 232 or 301 actions
Revenue concentration tied to politically sensitive sectors
Trade compliance data should be integrated into supply chain planning systems, not managed as a separate downstream function.
China Risk Remains Central
The ruling does not alter geopolitical dynamics.
Competition with China continues to drive trade policy. Section 301 authority remains intact. Export controls and related regulatory tools continue to evolve.
Diversification strategies that reduce concentrated China exposure remain strategically relevant.
Scenario Planning Should Reflect Statutory Triggers
Network design and landed cost models should be aligned to structured trade interventions.
Key planning questions include:
What is the impact of a Section 232 investigation affecting our category?
How would a targeted Section 301 action alter sourcing economics?
What operational flexibility exists during investigation timelines?
Organizations that can simulate these scenarios quickly will be better positioned to respond.
Refund Litigation Adds Operational Complexity
The Court did not address the disposition of tariffs already collected under the IEEPA framework. That issue now moves to lower courts.
Potential refund processes may require:
Administrative protests
Legal review
Financial adjustments
Finance, compliance, and supply chain functions should coordinate on exposure assessment and documentation readiness.
What to Watch
While emergency authority has been narrowed, trade policy remains active.
Expect continued:
Sector-based interventions
National security framing
Formal investigation processes
The structural shift is from emergency-based tariffs to statute-based tariffs.
Conclusion
The Supreme Court has imposed a constitutional boundary on emergency tariff powers. For supply chain leaders, this reduces one layer of unpredictability in global trade.
However, tariff risk remains embedded in the operating environment. It is now more structured and more procedural.
The post US Supreme Court Narrows Emergency Tariff Authority: Strategic Implications for Supply Chain Leaders appeared first on Logistics Viewpoints.
You may like
Non classé
The Systems-Engineered Logistics Operation: From Transformation Projects to Continuous Design
Published
17 heures agoon
3 novembre 2026By
For years, logistics transformation has been organized as a succession of projects. Implement the platform. Build the control tower. Automate the facility. Add the AI layer. The problem is that logistics no longer changes on a project cadence.
That environment is disappearing. The future logistics will need to be designed continuously. The Autonomous Logistics Network is one expression of this end state, but reaching it requires continuous design rather than a one-time transformation project.
Stop Thinking in Technology Stacks
Modern logistics networks are becoming integrated combinations of physical assets, software, data, optimization, AI, robotics, people, partners, and automated decisions. Calling this a technology stack understates what is happening.
It is an operating system. The important design questions are no longer confined to which applications a company owns. Leaders have to consider how decisions flow, how data maintain continuity across systems, how automation interacts with people, how models are governed, how exceptions escalate, and how the organization behaves when components fail.
That is systems engineering territory. The companies that manage this architecture deliberately will have an advantage over those that continue adding capabilities one project at a time.
Intelligence Is Moving to the Point of Action
Logistics technology is moving from systems of record toward systems of decision. Traditional applications captured transactions and supported workflows. Analytical systems added prediction and optimization. The emerging layer increasingly combines real-time signals, AI, optimization, agents, and execution connectivity.
The result is intelligence closer to the point of action. A shipment delay can be identified, its impact evaluated, alternatives generated, and a response executed with limited human intervention. Transportation systems can continuously re-evaluate routes, capacity, and exceptions instead of waiting for manual replanning. Warehouse and yard systems can adjust priorities as conditions change.
This will make logistics faster. It will also make architecture and governance more consequential.
When software only reported information, a bad output could be ignored. When software acts, the operating envelope matters.
Human Work Moves Up the Decision Stack
More automation does not eliminate the human role. It changes it.
People will spend less time collecting information, reconciling spreadsheets, monitoring routine transactions, and making repetitive bounded decisions. They will spend more time dealing with novel exceptions, cross-functional tradeoffs, strategic choices, carrier and customer relationships, system design, and governance.
That is a better use of human capability. It is also a harder job.
The future planner, transportation manager, warehouse leader, or logistics executive will need to understand not only operations but the automated systems influencing operations. They will need to know when to trust a recommendation, when to challenge it, and how a decision in one part of the system affects another. Logistics expertise will become more architectural.
Continuous Design Requires Continuous Validation
If the system changes continuously, validation must become continuous as well.
AI models drift. Business priorities change. automation rules evolve. New interfaces are added. Local process changes accumulate. External conditions move.
The organization cannot wait for the next transformation program to determine whether the operating system still meets its requirements. Performance, model behavior, exception patterns, overrides, decision latency, data quality, and failure modes will need ongoing monitoring.
This creates a closed lifecycle: design, deploy, observe, validate, improve, and redesign. Transformation becomes less of an event and more of a management discipline.
Resilience Becomes an Architectural Property
The future of resilience is also likely to move beyond static buffers. Inventory and redundancy will remain important, but digital systems will make logistics more capable of sensing, simulating, and responding dynamically.
A disruption can trigger scenario analysis. A digital twin can estimate consequences. Optimization can evaluate alternatives. AI can interpret unstructured signals. Automated decision systems can act inside approved boundaries.
This does not eliminate the need for physical resilience. It allows physical resilience and decision resilience to work together.
The strongest logistics networks will not simply carry more protection. They will understand their dependencies and reconfigure faster when conditions change.
Architecture Becomes a Competitive Capability
For years, companies differentiated logistics through network scale, facility and transportation assets, carrier leverage, operational excellence, service design, and technology investment. Architecture is becoming another source of advantage.
Two companies may use similar software and still achieve very different results because one has better process integration, clearer decision rights, stronger data, more effective automation boundaries, better failure recovery, and tighter governance. The advantage does not come from owning the component. It comes from how the components have been engineered to work together.
Logistics Management Becomes Systems Management
That may be the larger lesson of this series. Logistics networks are already systems of systems. The technology is making them more connected, more autonomous, and more adaptive. That complexity cannot be managed indefinitely through functional optimization and periodic implementation projects.
The discipline has to evolve.
Define requirements before selecting solutions. Design the operating model. Architect processes, data, and decisions together. Engineer technology into the system rather than around it. Validate the outcome. Govern change. Design for failure. Improve continuously.
The competitive advantage will not come from owning the same AI, automation, TMS, WMS, visibility, and execution technologies everybody else can buy. It will come from how coherently those components have been engineered to work together. The future of logistics management is not simply more digital, more autonomous, or more intelligent. It is more engineered.
Related Logistics Viewpoints research
Systems Engineering in Logistics
The New Architecture of Logistics
2026 Supply Chain Decision Intelligence Market Map
Digital Transformation in Logistics
Previous in this series: Design for Failure: Resilience, Risk, and Failure Modes
Request the Systems Engineering in Logistics Client Edition
If your organization is evaluating a logistics transformation, technology strategy, automation program, or operating-model redesign, I would be glad to provide the complete client edition and discuss how the framework applies to your priorities, constraints, and operating environment.
The post The Systems-Engineered Logistics Operation: From Transformation Projects to Continuous Design appeared first on Logistics Viewpoints.
Non classé
Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy
Published
17 heures agoon
3 novembre 2026By
Warehouse automation has traditionally been discussed one facility at a time. A retailer installs an automated storage system, deploys mobile robots, adds robotic picking, or upgrades sortation. The business case is then measured against improvements within that particular building. Walmart and Symbotic are beginning to challenge that way of thinking.
On October 29, Walmart and Symbotic announced an expanded commercial agreement that will bring additional automation capabilities to 25 U.S. regional distribution centers. The agreement includes an initial commitment of approximately $6 billion, covering work over several years and multiple locations. Walmart says the initiative is intended to support upstream e-commerce inventory management, increase storage capacity, and improve the movement of products through its supply chain. Those numbers make the announcement noteworthy. But the more interesting story is what the scale of the commitment says about the next phase of warehouse automation.
From an Automation Project to an Operating Model
For years, warehouse automation investments were frequently justified around specific bottlenecks: reduced picker travel, increase storage density, improve sortation throughput, or offset labor requirements. Those are still important objectives. But Walmart is evaluating automation against something larger: the performance of an interconnected distribution network supporting stores, pickup and home delivery.
Rob Montgomery, executive vice president for Walmart U.S. Supply Chain Operations, tied the expanded agreement to improving service, growing capacity, simplifying work for associates and lowering costs. The company also expects the expansion to support broader assortment, greater speed and more reliable replenishment. That distinction matters.
Warehouse automation increasingly needs to be evaluated not simply by asking, “How much faster can this facility pick?” but by asking, “What does this investment change across the supply chain?” Does additional storage capacity improve inventory positioning? Does automation enable later ordering cutoffs? Can replenishment become more predictable? Can the same technology architecture be repeated across multiple facilities without redesigning the operation every time? Those questions take warehouse automation discussions much closer to business strategy.
Scale Is Becoming Part of the Business Case
The Walmart-Symbotic relationship is particularly interesting because this is not a new pilot. Reuters reported that Symbotic has been helping automate Walmart’s supply chain since 2017, while the latest agreement extends automation to another 25 regional distribution centers. There is another layer to the expansion as well. Supply Chain Dive reported that Walmart committed an additional $125 million toward research and development of racking technology and related picking, process-flow and inventory-management capabilities. That is important because it suggests the competitive discussion is moving beyond individual pieces of robotic hardware. Warehouse automation is increasingly about how storage, picking, inventory, material movement and software operate together.
Symbotic’s current portfolio illustrates that evolution. The company says its integrated offering includes BreakPack for each-picking and SymMicro for e-commerce micro-fulfillment, supported by proprietary software that uses AI to orchestrate product movement. The question for warehouse operators, therefore, becomes less about which robot performs an individual task and more about how multiple automation layers combine into a repeatable operating system.
Walmart Is Not the Only Signal
Developments elsewhere reinforce the same trend. Amazon reported in 2026 that it has deployed more than one million robots across its operations network. Its systems now span inventory handling, mobile robotics, robotic arms and packaging automation. The company also says its Sequoia system can identify and store inventory up to 75 percent faster at fulfillment centers.
Meanwhile, DHL Supply Chain and Locus Robotics reached another useful measure of scale in 2026: one billion warehouse picks using Locus AMRs. Locus says thousands of its robots now operate across more than 40 DHL-managed sites worldwide. These examples are different applications with different economics. That is precisely the point. The warehouse automation market is moving beyond the question of whether robotics can work. Leading operators are increasingly confronting the harder questions of where automation should be deployed, how quickly it can scale, how well it integrates with existing operations, and whether benefits survive replication across a network.
The Metrics That Matter After Go-Live
The risk in covering a $6 billion automation agreement is treating announced spending as though it were demonstrated return. It is not. The more valuable story will develop as the systems go live. The measures worth watching include throughput, storage utilization, replenishment performance, labor productivity, system availability, fulfillment speed, implementation cost and the ability to maintain performance during demand peaks. That distinction should matter to technology buyers. A compelling demonstration can show what automation can do. A network-scale deployment begins to show whether the technology can generate similar value repeatedly under different facility and operating conditions. For Walmart, that makes the 25 distribution centers as important as the $6 billion headline.
Takeaway
The next chapter of warehouse automation will not be defined simply by more robots. It will be defined by whether operators can turn automation into a repeatable, measurable and scalable operating capability.
Walmart’s expanded relationship with Symbotic provides an unusually large test of that idea. The announced objectives are ambitious: more capacity, faster product movement, better replenishment, broader assortment, simpler work and lower costs. Now comes the more important part: measuring what changes when those systems are operating across the network. For other warehouse operators considering automation, that may ultimately be the most useful lesson from Walmart. Do not evaluate the robot alone. Evaluate what the automation changes in the economics and performance of the supply chain around it.
The post Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy appeared first on Logistics Viewpoints.
Non classé
Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy
Published
17 heures agoon
3 novembre 2026By
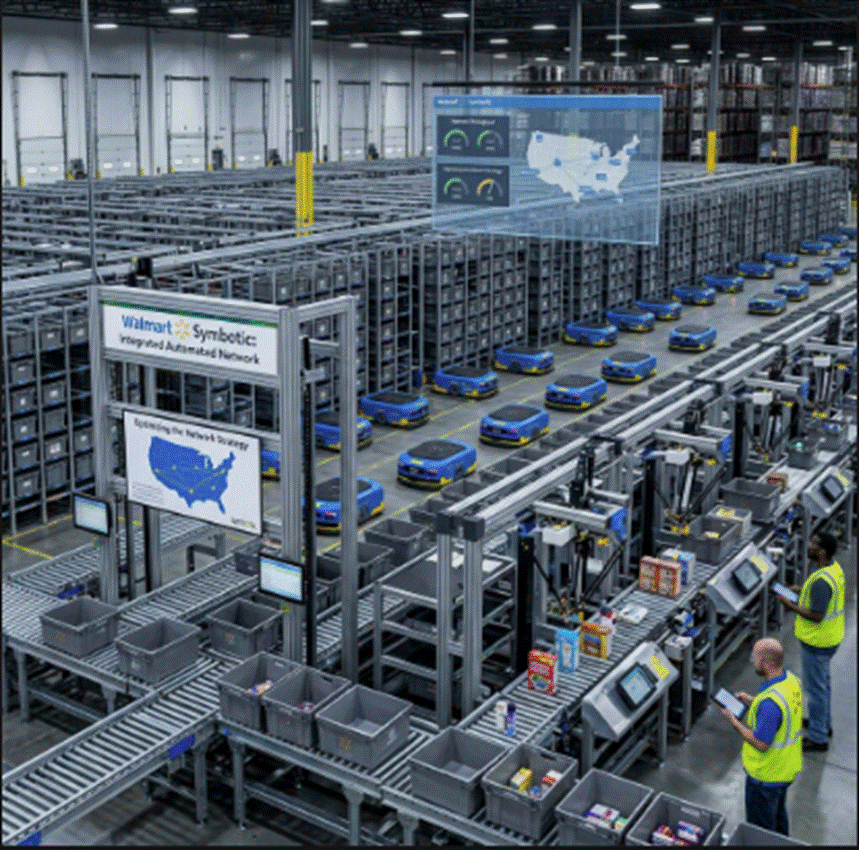
Warehouse automation has traditionally been discussed one facility at a time. A retailer installs an automated storage system, deploys mobile robots, adds robotic picking, or upgrades sortation. The business case is then measured against improvements within that particular building. Walmart and Symbotic are beginning to challenge that way of thinking.
On October 29, Walmart and Symbotic announced an expanded commercial agreement that will bring additional automation capabilities to 25 U.S. regional distribution centers. The agreement includes an initial commitment of approximately $6 billion, covering work over several years and multiple locations. Walmart says the initiative is intended to support upstream e-commerce inventory management, increase storage capacity, and improve the movement of products through its supply chain. Those numbers make the announcement noteworthy. But the more interesting story is what the scale of the commitment says about the next phase of warehouse automation.
From an Automation Project to an Operating Model
For years, warehouse automation investments were frequently justified around specific bottlenecks: reduced picker travel, increase storage density, improve sortation throughput, or offset labor requirements. Those are still important objectives. But Walmart is evaluating automation against something larger: the performance of an interconnected distribution network supporting stores, pickup and home delivery.
Rob Montgomery, executive vice president for Walmart U.S. Supply Chain Operations, tied the expanded agreement to improving service, growing capacity, simplifying work for associates and lowering costs. The company also expects the expansion to support broader assortment, greater speed and more reliable replenishment. That distinction matters.
Warehouse automation increasingly needs to be evaluated not simply by asking, “How much faster can this facility pick?” but by asking, “What does this investment change across the supply chain?” Does additional storage capacity improve inventory positioning? Does automation enable later ordering cutoffs? Can replenishment become more predictable? Can the same technology architecture be repeated across multiple facilities without redesigning the operation every time? Those questions take warehouse automation discussions much closer to business strategy.
Scale Is Becoming Part of the Business Case
The Walmart-Symbotic relationship is particularly interesting because this is not a new pilot. Reuters reported that Symbotic has been helping automate Walmart’s supply chain since 2017, while the latest agreement extends automation to another 25 regional distribution centers. There is another layer to the expansion as well. Supply Chain Dive reported that Walmart committed an additional $125 million toward research and development of racking technology and related picking, process-flow and inventory-management capabilities. That is important because it suggests the competitive discussion is moving beyond individual pieces of robotic hardware. Warehouse automation is increasingly about how storage, picking, inventory, material movement and software operate together.
Symbotic’s current portfolio illustrates that evolution. The company says its integrated offering includes BreakPack for each-picking and SymMicro for e-commerce micro-fulfillment, supported by proprietary software that uses AI to orchestrate product movement. The question for warehouse operators, therefore, becomes less about which robot performs an individual task and more about how multiple automation layers combine into a repeatable operating system.
Walmart Is Not the Only Signal
Developments elsewhere reinforce the same trend. Amazon reported in 2026 that it has deployed more than one million robots across its operations network. Its systems now span inventory handling, mobile robotics, robotic arms and packaging automation. The company also says its Sequoia system can identify and store inventory up to 75 percent faster at fulfillment centers.
Meanwhile, DHL Supply Chain and Locus Robotics reached another useful measure of scale in 2026: one billion warehouse picks using Locus AMRs. Locus says thousands of its robots now operate across more than 40 DHL-managed sites worldwide. These examples are different applications with different economics. That is precisely the point. The warehouse automation market is moving beyond the question of whether robotics can work. Leading operators are increasingly confronting the harder questions of where automation should be deployed, how quickly it can scale, how well it integrates with existing operations, and whether benefits survive replication across a network.
The Metrics That Matter After Go-Live
The risk in covering a $6 billion automation agreement is treating announced spending as though it were demonstrated return. It is not. The more valuable story will develop as the systems go live. The measures worth watching include throughput, storage utilization, replenishment performance, labor productivity, system availability, fulfillment speed, implementation cost and the ability to maintain performance during demand peaks. That distinction should matter to technology buyers. A compelling demonstration can show what automation can do. A network-scale deployment begins to show whether the technology can generate similar value repeatedly under different facility and operating conditions. For Walmart, that makes the 25 distribution centers as important as the $6 billion headline.
Takeaway
The next chapter of warehouse automation will not be defined simply by more robots. It will be defined by whether operators can turn automation into a repeatable, measurable and scalable operating capability.
Walmart’s expanded relationship with Symbotic provides an unusually large test of that idea. The announced objectives are ambitious: more capacity, faster product movement, better replenishment, broader assortment, simpler work and lower costs. Now comes the more important part: measuring what changes when those systems are operating across the network. For other warehouse operators considering automation, that may ultimately be the most useful lesson from Walmart. Do not evaluate the robot alone. Evaluate what the automation changes in the economics and performance of the supply chain around it.
The post Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy appeared first on Logistics Viewpoints.

The Systems-Engineered Logistics Operation: From Transformation Projects to Continuous Design
Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy
Walmart and Symbotic: When Warehouse Automation Becomes a Network Strategy
Freightos Global Freight Outlook – September 2026
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update

Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
Trending
- Non classé2 mois ago
Freightos Global Freight Outlook – September 2026
- Non classé4 mois ago
Container rates jump another $1k/FEU – but is demand peaking? – July 8, 2026 Update
-
 Non classé2 ans ago
Walmart and the New Supply Chain Reality: AI, Automation, and Resilience
-
 Non classé7 mois ago
Why Sulfuric Acid Is Emerging as a Supply Chain Constraint in Copper
- Non classé5 mois ago
Container rates starting to spike on peak season rush – June 2, 2026 Update
- Non classé1 an ago
13 Books Logistics And Supply Chain Experts Need To Read
- Non classé1 an ago
Ex-Asia ocean rates climb on GRIs, despite slowing demand – October 22, 2025 Update
- Non classé4 mois ago
LCL Shipping Cost Calculator: Calculate Air and Sea Shipping Freight Rates